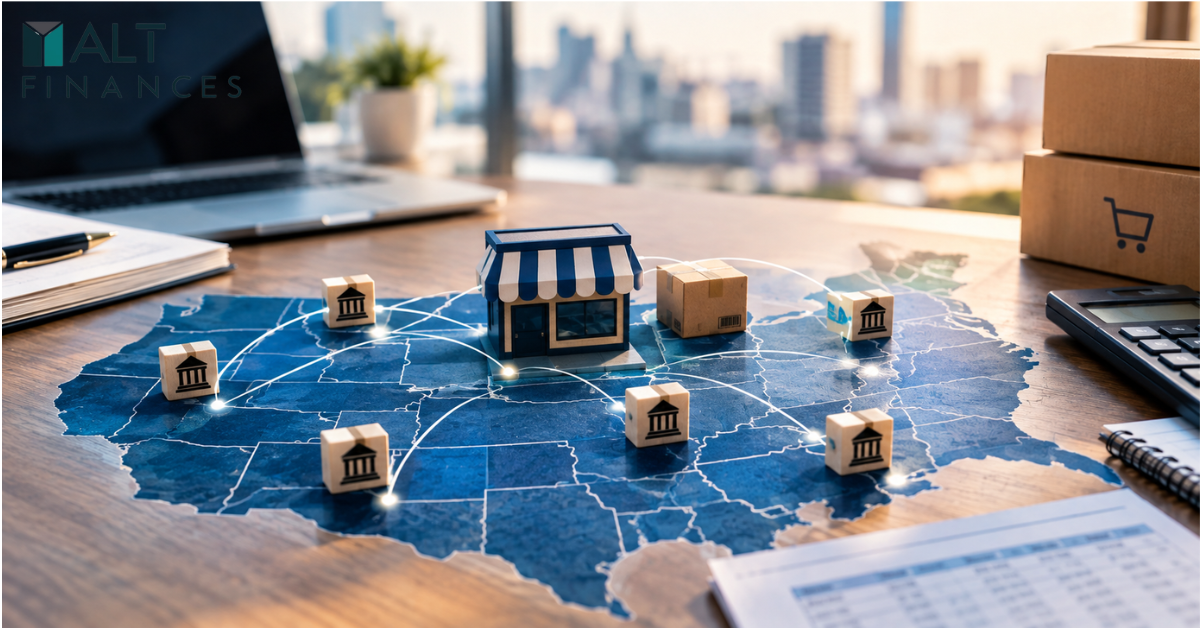
A startup can be headquartered in one state, have no office in another, and still create a tax obligation there. As online sales, SaaS subscriptions, digital services and marketplace transactions allow young companies to reach customers nationwide almost immediately, startup nexus has become an important compliance issue.
The difficult question is not simply where a business is located. It is where the business is selling, how much activity it has in each state, what it is selling, and whether its activities create a state tax collection responsibility.
That distinction matters because interstate growth can create compliance obligations before founders realize that their business has crossed a state-specific threshold.
Why Startup Growth Can Create Unexpected Tax Exposure
A startup can expand geographically without opening traditional locations.
An e-commerce company may ship products to customers across the country. A SaaS company can acquire subscribers in dozens of states without sending employees there. A digital business can sell subscriptions or downloadable products entirely online. A marketplace can connect sellers and buyers across state lines.
The same technology that makes national growth inexpensive can also create a fragmented tax footprint.
For founders, the relevant sequence is:
Growth → Interstate Sales → Nexus → Registration → Collection → Filing
The important point is that the rules do not treat every interstate sale the same way.
What Is Startup Nexus?
Nexus is the connection between a business and a state that can give the state authority to impose certain tax or compliance obligations.
For sales-tax purposes, that connection can arise through several routes.
Physical nexus can result from activities such as employees, inventory, offices, warehouses or other forms of physical presence. Trade shows and other in-state activities can also matter depending on the state’s rules.
Economic nexus is different. A business may create nexus through the amount or volume of its economic activity in a state even without a traditional physical presence.
Affiliate or attribution-based nexus can arise when relationships or activities involving related parties or other in-state connections are treated as creating a sufficient connection under state law.
Marketplace nexus adds another layer for businesses selling through platforms. Marketplace-facilitator laws in many states shift some collection responsibilities to the platform, but sellers still need to understand how those sales are treated under the applicable state’s rules.
These categories should not be treated as interchangeable. The applicable standard depends on the state and the facts.
Economic Nexus Changed the Rules for Remote Sellers
The modern remote-seller environment was fundamentally changed by the U.S. Supreme Court’s 2018 decision in South Dakota v. Wayfair.
Before Wayfair, the constitutional debate around sales-tax collection by remote sellers was closely associated with physical presence. The Supreme Court rejected the idea that physical presence was an absolute requirement for a state to impose collection responsibilities on a remote seller.
The decision opened the door for states to establish economic-nexus standards.
But Wayfair did not create one nationwide sales threshold.
States subsequently adopted their own economic-nexus rules. As of 2026, every state with a general sales tax has an economic-nexus framework for remote sellers, but the details differ. States can use different revenue thresholds, transaction tests, measurement periods and definitions of which sales count toward the threshold.
That is why founders should avoid relying on a single national rule.
When Does Selling Into Another State Trigger Economic Nexus?
The basic question is whether a startup’s activity reaches the threshold established by the state.
That can involve:
- Sales revenue
- Number of transactions
- Measurement period
- Type of sales included
- Taxable or nontaxable sales
- Retail versus wholesale sales
- Marketplace transactions
- State-specific registration rules
Some states use a sales threshold. Others have used a sales threshold combined with or historically paired with a transaction test. The amount and calculation method can also vary.
For example, a state may calculate its threshold using gross sales, while another rule may focus on retail or taxable sales. The same startup could therefore calculate its exposure differently depending on the jurisdiction.
This is one reason the familiar $100,000 or 200 transactions formulation should not be treated as a universal rule. Current state guidance shows meaningful differences in both thresholds and how sales are counted.
The question is not simply, “Did we make $100,000 of sales?”
It is:
“What sales count under this state’s current nexus rule, during which measurement period, and what happens after the threshold is reached?”
Physical Presence Still Matters for Startups
Economic nexus did not eliminate physical nexus.
A startup can create a state connection through employees, contractors, inventory, warehouses, offices or other in-state activities even when its sales volume is relatively modest.
Inventory deserves particular attention. A startup that uses a third-party fulfillment arrangement or stores products in another state may need to examine whether that physical presence creates registration or collection obligations.
Employees and contractors can also matter. A growing technology company may have remote workers in several states without thinking of those locations as tax jurisdictions. Depending on the state’s rules and the nature of the activity, however, people working from another state can create important tax consequences.
The lesson is straightforward: founders should monitor where the business operates, not only where customers live.
SaaS, Digital Products and Services Create Additional Complexity
SaaS startups face a particularly difficult issue because states do not necessarily treat software and digital services in the same way.
A subscription to cloud-based software, a downloadable digital product and a professional service may receive different tax treatment depending on the jurisdiction.
Even when a startup has established nexus, that does not automatically mean every sale is taxable.
The company must separately determine whether the product or service is taxable under the applicable state’s rules and how the transaction should be sourced.
That makes SaaS tax compliance more than a simple revenue-threshold exercise.
For a fast-growing software company, the taxability question should be reviewed alongside the nexus question.
What About Amazon, Marketplaces and Other Platforms?
Marketplace facilitators have changed the compliance burden for many online sellers.
In numerous states, laws require marketplaces to collect and remit sales tax on transactions conducted through their platforms. This can reduce the seller’s direct collection responsibility for covered transactions.
But founders should not assume that marketplace sales can simply be ignored.
States differ in how marketplace sales are treated when determining economic-nexus thresholds and whether sellers have separate registration or reporting responsibilities. A business selling both directly through its website and through a marketplace may therefore need to track the channels separately.
The practical answer is better data, not assumptions.
The Hidden Cost of Getting Nexus Wrong
The financial risk of an unresolved sales-tax obligation is not limited to the tax itself.
A startup that should have registered and collected tax may later face additional administrative work, including historical filings, tax assessments, interest or penalties where applicable, and reconciliation of customer transactions.
The issue can also emerge during fundraising, an acquisition, an audit or a broader tax review.
That makes state-tax exposure an operating-risk issue as well as a compliance issue.
For investors and acquirers, unresolved multistate obligations can raise questions about the quality of a company’s financial controls and whether reported revenue properly reflects its tax responsibilities.
A rapidly growing startup therefore has an incentive to identify exposure before an external party does.
What Founders Should Monitor Before Expanding Across State Lines
A practical monitoring system should answer ten questions:
- Where are our customers located?
- How much revenue comes from each state?
- How many transactions occur in each state?
- Are the products or services taxable there?
- Do we have employees or contractors in the state?
- Do we hold inventory or use fulfillment facilities there?
- Are sales made directly or through marketplaces?
- What measurement period does the state use?
- When does registration become necessary?
- Do we already have historical exposure?
This information should be monitored continuously rather than reviewed only when the company prepares its annual accounts.
Unique Insight — Startup Growth Can Create Tax Exposure Before Founders Realize It
The deeper issue with startup nexus is that modern growth and tax exposure can develop at the same time.
A founder sees national customers as evidence of product-market fit. A tax authority may see the same activity as an expanding economic connection with its state.
That creates a new operating reality:
Rapid Growth → Geographic Expansion → State-Level Activity → Nexus → Compliance Burden
The tax question is therefore no longer simply where the startup is located. It is increasingly about where the startup is economically active and what it is selling.
For investors, this distinction matters because a startup’s geographic reach can create obligations that do not appear obvious from its headquarters, employee count or balance sheet.
Conclusion
Interstate growth can create sales-tax responsibilities without a startup opening an office, warehouse or storefront in another state.
But selling into another state does not automatically create the same obligation everywhere. Startup nexus depends on state law, economic activity, physical presence, the nature of the product or service, marketplace arrangements and applicable thresholds.
The most important distinction is between nexus, taxability, collection, registration and filing. They are connected, but they are not the same question.
For founders, the practical response is to monitor sales and business activity by state as the company scales. Waiting until a tax notice, audit, financing event or acquisition exposes a compliance gap can turn a manageable administrative issue into a much larger business problem.
Frequently Asked Questions
What is startup nexus?
Startup nexus is the connection between a startup and a state that can create tax or compliance obligations. For sales tax, that connection can arise through physical presence, economic activity or other state-specific rules.
Does selling into another state automatically create a tax obligation?
No. A sale alone does not automatically create the same obligation in every state. The applicable state’s nexus rules, the nature of the sale and the company’s other activities must be considered.
What is economic nexus for a startup?
Economic nexus generally means that a remote seller has sufficient economic activity in a state to trigger sales-tax registration and collection responsibilities under that state’s law, even without a traditional physical presence.
Do SaaS startups have to collect sales tax in every state?
No. SaaS and other digital products or services can receive different tax treatment by jurisdiction. A startup must examine both whether it has nexus and whether its particular offering is taxable in that state.
What should a startup do after it crosses a state’s nexus threshold?
The company should review the state’s current registration, collection and filing requirements promptly. It should also determine which sales count toward the threshold and whether any historical exposure exists. Because state rules change, founders should verify the requirements with the relevant state tax authority or qualified adviser.
Investment & Tax Disclaimer
This article provides general informational content and does not constitute financial, investment, legal, tax, accounting or other professional advice.
State and local tax laws vary by jurisdiction and can change over time. Businesses should independently verify applicable requirements and consult qualified tax, accounting or legal professionals regarding their specific circumstances.
Marcie Bilawsky
Marcie Bilawsky is a Financial Writer & Research Contributor at AltFinances, covering investing, alternative assets, wealth management, and global financial markets. Her work focuses on making complex financial trends, investment themes, and emerging market opportunities easier to understand through research-driven analysis.