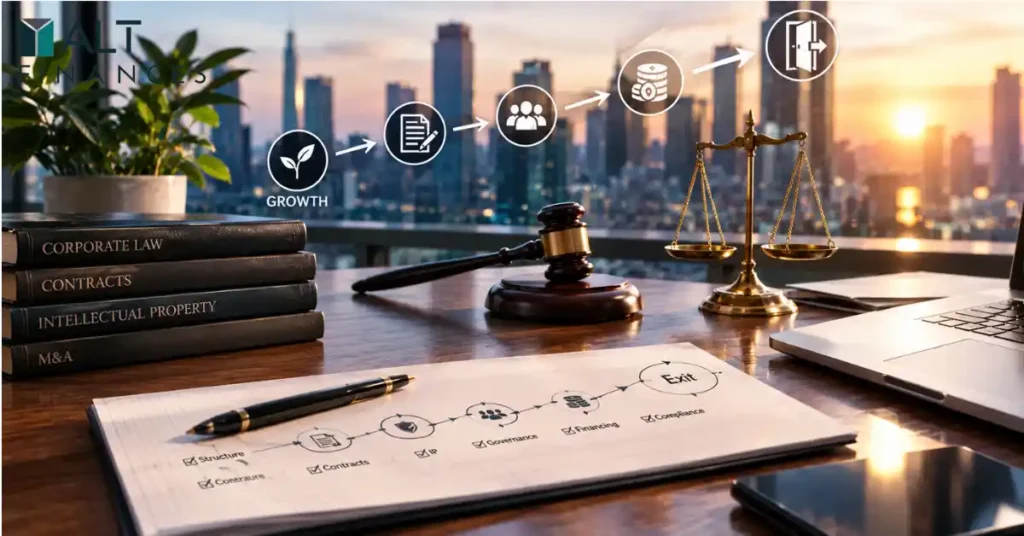
Business owners often think about value in terms of revenue, profit, growth and market share. Those numbers matter, but they are not the whole story.
When a business is eventually sold, merged, recapitalized or brought to investors, buyers look at something deeper: how transferable, defensible and sustainable is the business?
Legal decisions made years before an exit can influence that answer.
The company’s structure, ownership records, contracts, intellectual property, employment arrangements, financing documents and governance practices can either support a transaction or create additional risk that affects its terms.
The important point is simple: exit preparation does not begin when a buyer appears. It begins with the decisions made while the business is growing.
Business Value Is More Than Financial Performance
A profitable company can still be difficult to sell.
Consider two businesses with similar revenue and EBITDA. One has documented contracts, clean intellectual-property ownership, organized corporate records and a management team capable of operating without its founder.
The other depends heavily on the owner, has informal customer arrangements, unclear IP ownership and several unresolved legal issues.
Their financial statements may look similar, but a buyer may view their risk very differently.
Business valuation is influenced by financial performance, future growth expectations, market conditions and perceived risk. Legal structure can affect that risk by determining how clearly the business owns its assets, controls its relationships and can transfer its operations.
This is why legal work should not be viewed merely as paperwork around an eventual transaction.
Legal structure is part of the business’s economic infrastructure.
Choose a Structure That Supports Future Growth
The choice of entity can affect governance, ownership, financing and ultimately an exit.
U.S. businesses commonly operate through corporations, LLCs and other structures, each with different legal and tax characteristics.
The right structure depends on the business, its owners, financing plans, tax position and state law. A structure that works for a small owner-operated company may not be ideal after institutional investment or a planned acquisition.
The important issue is not simply choosing a structure at formation.
It is reviewing whether the existing structure continues to fit the company’s objectives as it grows.
A company preparing for outside investment or a future sale should have clear ownership records, properly authorized equity issuances and consistent corporate documentation.
A buyer should not have to reconstruct who owns the company.
Keep Ownership and Governance Records Clean
Ownership disputes can become particularly damaging when a company is preparing for a transaction.
Founders and shareholders should understand:
- Who owns the outstanding equity
- Whether all issuances were properly authorized
- What options or warrants are outstanding
- Whether convertible securities exist
- What shareholder agreements provide
- Who has voting rights
- Whether transfer restrictions apply
- Whether any buy-sell provisions could affect a transaction
A clean capitalization table is important, but it is only one part of the picture.
Shareholder agreements and governing documents can also contain provisions affecting a future sale, including consent requirements, transfer restrictions, drag-along rights and tag-along rights.
These provisions can determine not only whether a transaction can proceed, but also who has influence over the process.
Contracts Can Protect or Reduce Business Value
A business may have excellent revenue and still carry contractual problems that a buyer considers material.
Important agreements should be reviewed for:
- Assignment restrictions
- Change-of-control provisions
- Termination rights
- Exclusivity obligations
- Minimum commitments
- Long-term liabilities
- Renewal provisions
- Customer concentration
- Supplier dependencies
For example, a company may depend on a major customer under a contract that allows termination following a change of control.
That customer relationship may look like a valuable asset in a financial model, but its value can change substantially if an acquisition triggers a termination right.
The same principle applies to leases, supplier agreements, distribution arrangements, licensing agreements and other material contracts.
Revenue is more valuable when the legal relationship supporting that revenue is durable and transferable.
Protect Intellectual Property Before the Exit
Intellectual property can be one of the most valuable assets in a technology, media, healthcare, manufacturing or professional-services business.
But ownership needs to be clear.
Businesses should understand whether their trademarks, software, inventions, content, designs, databases and other proprietary assets are actually owned by the company.
This becomes particularly important where founders, employees, consultants or outside developers created the IP.
Written assignment and confidentiality agreements can help establish the company’s rights, but the specific requirements depend on the type of intellectual property and applicable law.
A buyer conducting due diligence will want evidence that the business has the rights it claims to possess.
An IP ownership problem discovered shortly before closing can create delays, additional negotiations or a reduction in transaction certainty.
Reduce Founder Dependency
One of the most overlooked sources of business risk is dependence on the founder.
A company may have strong revenue but still rely on one individual for:
- Major customer relationships
- Sales
- Product knowledge
- Operational decisions
- Supplier relationships
- Technical expertise
- Hiring decisions
That dependence can make the business harder to transfer.
A buyer is not simply purchasing historical performance. The buyer is purchasing an operating business that is expected to continue generating value after the transaction.
The more the company’s knowledge, relationships and decision-making are embedded in its systems and team, rather than one person, the easier it may be to demonstrate operational continuity.
This does not mean founders are unimportant. It means the business should become capable of functioning without every important decision passing through the founder.
Employment Arrangements Can Affect Exit Readiness
Employees can represent significant operational value, but employment relationships can also create transaction risks.
Businesses should maintain appropriate employment agreements, confidentiality provisions, intellectual-property arrangements and records.
Depending on the business and applicable law, buyers may also examine wage-and-hour compliance, employee classification, benefits, restrictive covenants and employment-related disputes.
The goal is not to eliminate every employment risk. It is to identify and manage material issues before they become transaction problems.
A buyer generally wants to know whether the workforce needed to operate the business will remain available and whether there are undisclosed employment liabilities.
Financing Decisions Can Follow the Business to the Exit
Capital raised during the growth phase can affect an eventual sale.
Debt agreements may contain:
- Change-of-control provisions
- Mandatory repayment requirements
- Financial covenants
- Security interests
- Consent requirements
Investor agreements can contain:
- Preferred rights
- Voting provisions
- Protective provisions
- Conversion rights
- Drag-along rights
- Tag-along rights
- Distribution preferences
These provisions may have been reasonable when the financing was completed. But years later, they can influence how an exit is structured.
The question is therefore not simply:
“How much capital can we raise?”
It is also:
“What rights are we giving away, and how might those rights affect a future transaction?”
Litigation and Compliance Can Change the Risk Profile
Pending litigation, regulatory problems, intellectual-property disputes or unresolved contractual claims can affect a buyer’s assessment of a business.
Not every dispute destroys value.
The important issue is whether the potential liability is understood, properly documented and reflected in the transaction analysis.
Businesses should maintain appropriate records of material disputes, regulatory matters and compliance obligations.
A problem discovered early can often be managed more effectively than the same problem discovered immediately before closing.
Build a Business That Can Survive Due Diligence
Due diligence is where many years of legal and operational decisions eventually come together.
A buyer may review:
- Corporate records
- Ownership and capitalization
- Material contracts
- Intellectual property
- Employment matters
- Litigation
- Regulatory compliance
- Debt and financing
- Tax matters
- Assets and liabilities
This is not simply a search for mistakes.
It is an attempt to determine whether the business being purchased is actually what the seller represents it to be.
The strongest position is therefore not to create a perfect-looking data room at the last minute.
It is to build a company whose documentation consistently reflects how the business actually operates.
Choose the Exit Structure Carefully
There is no single way to sell or transition a business.
Depending on the circumstances, a transaction might involve an asset sale, stock sale, merger, recapitalization or another structure.
The choice can affect the buyer, seller, liabilities, contracts, approvals and tax consequences.
The federal tax treatment of a business transaction can also depend on what is actually being transferred. For example, the IRS generally treats a lump-sum sale of a trade or business as a sale of individual assets for federal tax purposes, requiring allocation of consideration among the assets in relevant circumstances.
That is why legal, financial and tax advisers should evaluate the transaction structure together rather than treating the purchase agreement as an isolated document.
Do Not Wait Until a Buyer Appears
One of the most expensive mistakes is beginning legal cleanup after receiving an acquisition offer.
At that point, the seller may have limited time to correct:
- Missing IP assignments
- Incomplete corporate records
- Unclear ownership
- Problematic contracts
- Undocumented shareholder arrangements
- Founder dependency
- Unresolved disputes
A better approach is periodic legal housekeeping.
The business does not need to be preparing for an immediate sale.
It simply needs to be operated as though a sophisticated buyer may eventually ask difficult questions.
Unique Insight: Transferability Is Part of Value
The central issue is transferability.
A business creates value when it generates revenue and profit. It creates stronger transaction value when those economic benefits can be transferred to another owner with reasonable confidence.
That means:
Revenue + Sustainable Operations + Clear Ownership + Enforceable Contracts + Protected IP + Strong Governance = Transferable Business Value
The legal function is therefore not separate from the financial value of the business.
It helps establish whether the assets generating that value can actually be transferred, defended and relied upon.
A buyer is not paying only for what the company has achieved.
The buyer is paying for confidence that the company can continue producing those results after ownership changes.
A Legal Readiness Checklist for Business Owners
Before pursuing a major investment, sale or strategic transaction, owners should consider whether they can clearly answer:
Who owns the business?
The capitalization and ownership records should be accurate and current.
Who owns the intellectual property?
The company should have appropriate rights to the IP it relies upon.
Which contracts are essential?
Material customer, supplier, licensing and other agreements should be identified and reviewed.
Can key contracts survive a change of control?
Restrictions or consent requirements should be understood before a transaction begins.
Can the company operate without the founder?
Important relationships and processes should not depend entirely on one individual.
Are financing obligations understood?
Debt and investor documents should be reviewed for provisions triggered by a transaction.
Are there unresolved legal risks?
Material litigation, compliance issues and contractual disputes should be identified.
Are the corporate records organized?
Ownership, governance and authorization records should tell a consistent story.
Conclusion
The value of a business is not created at the closing table.
It is built over years through financial performance, customer relationships, intellectual property, people, contracts, systems and strategic decisions. Legal decisions are woven into each of those areas.
A company with strong earnings but weak legal foundations may face unnecessary friction during a transaction. A company with comparable financial performance and well-organized legal and operational foundations may offer a buyer greater confidence.
That is why from growth to exit, the legal objective should be more than avoiding disputes.
It should be to build a business that is owned clearly, governed properly, contractually protected, operationally resilient and capable of being transferred.
The earlier those principles are incorporated into the company’s growth strategy, the more options the owner may have when the time comes to realize the value that has been built.
Frequently Asked Questions
Can legal decisions really affect the value of a business?
Yes. Ownership uncertainty, contract restrictions, IP problems, litigation, governance weaknesses and other legal risks can affect a buyer’s assessment of transaction risk and the structure of a deal.
When should a business owner start preparing for an exit?
There is no universal timetable, but exit readiness is generally stronger when legal and operational issues are managed throughout the company’s growth rather than addressed immediately before a transaction.
Why does intellectual-property ownership matter when selling a business?
A buyer needs confidence that the company owns or has sufficient rights to the intellectual property that supports its products, services or competitive advantage.
Can a founder’s involvement affect business value?
Yes. Significant dependence on a founder can create continuity risk because a buyer must assess whether the business can continue operating effectively after the transaction.
Do contracts affect a company’s sale value?
They can. Material contracts provide the legal foundation for customer revenue, suppliers, licenses and other relationships. Assignment or change-of-control restrictions can affect how a transaction is structured.
Does the type of business sale affect taxes?
Yes. The federal tax consequences can differ depending on what is sold and how the transaction is structured. The IRS specifically provides rules for allocating consideration among assets in certain business asset sales.
Legal Disclaimer: This article is for general informational and educational purposes and does not constitute legal, tax, accounting, investment or other professional advice. U.S. laws vary by state and transaction structure. Business owners should obtain advice from qualified professionals regarding their particular circumstances before entering into an investment, sale, merger or other transaction.
David Seidman is the Principal of Seidman Law Group LLC, where he serves as outside general counsel for small to mid-sized companies. A seasoned legal advisor and entrepreneur, he specializes in contract negotiation, commercial litigation, and strategic risk management across the hospitality and finance sectors.