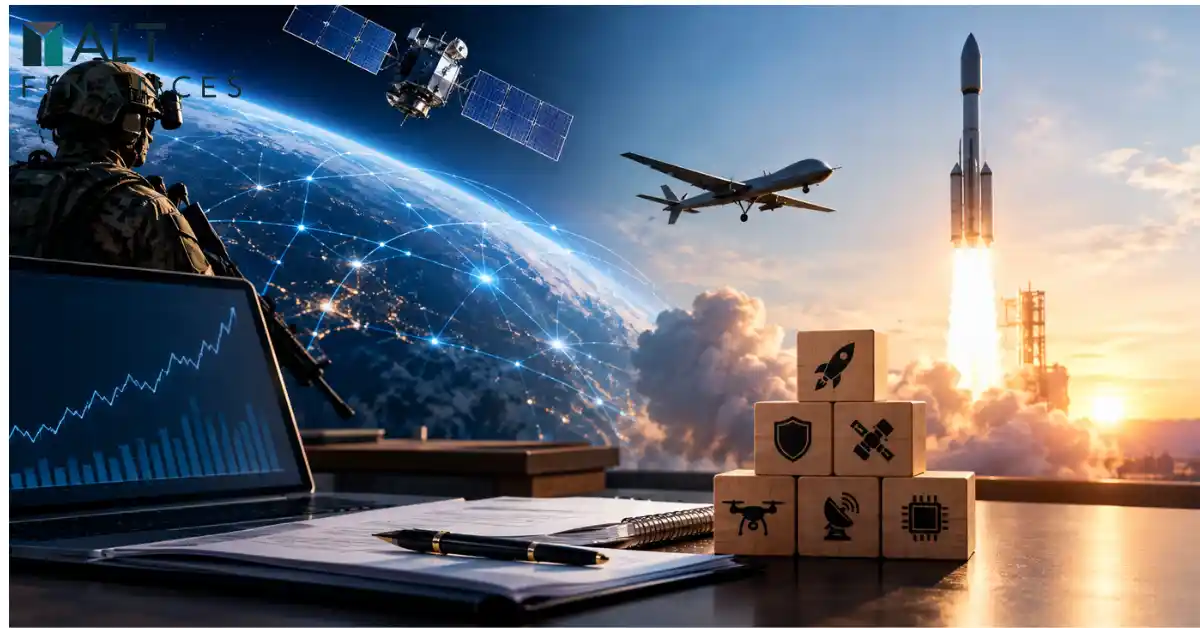
The new security economy is pulling defense and space technology into a much broader private-capital ecosystem. Companies building drones, satellites, propulsion systems, autonomous platforms and other dual-use technologies are attracting investors looking beyond traditional defense contractors.
The defense space SPAC boom is one visible sign of that shift. In 2026, more early-stage defense and space companies have turned toward special purpose acquisition companies (SPACs) as a route to public markets, while investors have shown renewed interest in technologies linked to national security, commercial space and advanced manufacturing.
The investment story, however, is bigger than SPACs. It reflects a convergence of geopolitical risk, government demand, technology development and private capital.
Why Defense and Space Have Become Private-Capital Targets
Defense and space were once relatively specialized investment markets. Today, their boundaries are changing.
Governments are placing greater emphasis on resilient supply chains, autonomous systems, communications, sensing, cybersecurity and space infrastructure. At the same time, technologies developed for commercial markets can increasingly serve government customers.
That creates opportunities across areas such as drones, counter-drone systems, satellites, launch technology, electronic warfare, advanced manufacturing, cybersecurity and artificial intelligence.
The attraction for private investors is not simply higher government spending. Defense and space companies can also possess specialized technology, difficult-to-replicate manufacturing capabilities and long development cycles that can create barriers to entry.
But strategic importance does not automatically create an attractive investment. Government demand can improve revenue visibility without guaranteeing margins, profitability or shareholder returns.
The Defense Space SPAC Boom Is Bringing Private Companies Toward Public Markets
The current SPAC revival is giving some defense and space companies another route from private ownership to public markets.
Reuters reported on September 14 that several defense and space companies were pursuing SPAC combinations, including Ursa Major, Sierra Space, Quantum Space and Elroy Air. The attraction is partly structural: private companies can negotiate valuations with a SPAC sponsor and arrange financing before completing a public listing, rather than relying entirely on the traditional IPO process.
The broader SPAC market has also returned in force. Reuters reported that 143 SPAC IPOs had taken place by September 2026, raising approximately $28 billion. Yet the resurgence comes with an important warning: SPAC enthusiasm has historically produced mixed results for investors.
A SPAC therefore provides a financing and listing mechanism, not a validation of a company’s technology or valuation.
The basic process remains:
SPAC Formation → Target Selection → Valuation → Financing → Shareholder Approval → Merger → Public Listing
Each stage can affect the eventual ownership and economics of the company.
Why Dual-Use Technology Is Changing the Investment Case
One of the most important developments is the rise of dual-use technology.
A company may develop technology for a commercial market while also serving defense or government customers. Autonomous systems, satellite communications, sensors, artificial intelligence and cybersecurity can all have applications across both markets.
That can potentially create multiple sources of demand.
A drone platform, for example, may have commercial applications while also supporting defense operations. Satellite technology can serve communications, earth observation or national-security functions. Advanced software can support commercial infrastructure while also being adapted for government applications.
For investors, the important question is whether the company can actually convert this technological overlap into sustainable revenue.
Having a potential government application is not the same as having a contract. Having a contract is not the same as having profitable production.
That distinction becomes particularly important when valuations rise quickly.
Space Is Becoming Part of the Security Economy
Space is increasingly connected to communications, intelligence, navigation, earth observation and national-security infrastructure.
Private capital is consequently moving beyond launch companies and toward the broader supply chain supporting the space economy.
NASA and the Small Business Administration launched the SBIC-NASA Initiative in 2026 to expand investment in American companies supporting critical space technologies and supply chains. The initiative identifies areas including energy, nuclear power and propulsion, software, avionics, communications, specialized materials and launch infrastructure.
NASA has also continued using its small-business programs to support early-stage technologies. In August, the agency selected 51 Phase I proposals under one SBIR/STTR group and 121 under another, with each selected company receiving $225,000 for feasibility work.
These programs do not make every recipient an investment opportunity. They do, however, illustrate how public institutions are helping develop the industrial base that private investors may later finance.
What Makes Defense and Space Companies Attractive to Private Capital?
Several characteristics can make the sector interesting to private-equity, venture-capital and growth investors.
First is long-term government demand. National-security requirements can support demand for technologies that governments consider strategically important.
Second is technology specialization. Aerospace manufacturing, propulsion, sensing and advanced defense systems often require expertise, certification and infrastructure that new competitors cannot easily reproduce.
Third is dual-market potential. A company that serves both government and commercial customers may have more than one route to revenue.
Fourth is strategic infrastructure. Satellites, communications networks, launch systems and specialized components increasingly sit within broader economic and security systems.
But these advantages need to be tested at the company level. Investors still need evidence of technology readiness, production capability, customer demand and sustainable economics.
The Risks Behind the Defense Space SPAC Boom
The biggest mistake would be to interpret rising investor interest as proof that valuations are justified.
SPAC transactions can involve dilution, redemption risk, sponsor economics and valuation uncertainty. Additional financing, including PIPE transactions, can also change the ownership structure.
Defense companies face another layer of risk: government procurement.
Contracts can take time to award, programs can change, customers can be concentrated and production can be more difficult than the original technology demonstration suggests.
Space companies face their own challenges, including capital intensity, launch risk, regulatory constraints and technology development risk.
The broader SPAC market provides a useful warning. Reuters reported that only a minority of recent SPAC deals were trading above the original $10 IPO price, while many had fallen substantially below it. That history shows why a successful merger announcement should not be confused with successful long-term investment performance.
What Investors Should Examine Before Backing a Defense or Space SPAC
Investors should look beyond the headline technology.
Technology readiness: Has the product moved beyond a demonstration?
Government contracts: Are agreements firm, funded and commercially meaningful?
Backlog: How much contracted demand exists, and over what period?
Customer concentration: Does one government agency or contractor account for most revenue?
Production: Can the company manufacture at the required scale?
Capital requirements: How much additional funding will the business need?
Unit economics: Can the company eventually generate attractive margins?
Procurement cycles: How long can customers take to approve and deploy the technology?
SPAC terms: What are the sponsor economics, redemption structure and financing arrangements?
Dilution: How much of the eventual company will existing investors actually own?
Valuation: Does the proposed valuation reflect current revenue and economics, or mostly future expectations?
These questions help separate an attractive technology from an attractive security.
Unique Insight The Security Economy Is Becoming a Private-Capital Asset Class
The defense space SPAC boom is not simply a story about SPACs.
It reflects a broader shift in how national-security capabilities are being developed and financed.
The traditional model was largely:
Government → Prime Contractor → Procurement
The emerging model is more complicated:
Government Demand → Technology Startup → Private Capital → Commercialization → Government and Commercial Customers → Public Markets
That matters for alternative investors because defense and space are increasingly intersecting with venture capital, private equity, infrastructure and public markets.
The result is a developing security economy in which private capital can finance technologies that eventually serve both commercial markets and national-security requirements.
But the investment opportunity depends on whether companies can cross the difficult gap between technology potential and commercial execution.
Conclusion
The defense space SPAC boom reflects more than renewed enthusiasm for a financial structure.
It is part of a larger movement toward private financing of defense technology, space infrastructure and dual-use systems. Geopolitical pressures, government demand and technological advances are expanding the addressable market for companies operating in these sectors.
For investors, however, strategic importance should not be confused with investment quality.
Government demand can provide revenue visibility without guaranteeing profitability. A strong technology can still fail commercially. A major contract can still involve procurement delays. And a SPAC listing can create public-market access while also introducing dilution and valuation risks.
The opportunity is therefore best understood through several separate questions:
Is the technology real? Is demand durable? Can the company manufacture? Can it generate sustainable revenue? And is the valuation reasonable?
The defense space SPAC boom may continue to attract capital, but the strongest opportunities are likely to be determined not by the SPAC label, but by the underlying economics of the companies entering the public market.
Frequently Asked Questions
What is the defense space SPAC boom?
The defense space SPAC boom describes the renewed use of SPAC mergers by defense and space companies seeking public-market access amid stronger investor interest in national-security and dual-use technologies.
Why are private investors increasing exposure to defense and space companies?
Investors are examining the sectors because of government demand, geopolitical priorities, technological barriers and the growing commercial applications of defense and space technologies.
Why are defense and space startups using SPACs?
SPACs can provide an alternative route to public markets and allow companies to negotiate valuations and financing arrangements before completing a merger. They do not eliminate the risks associated with becoming a public company.
What are dual-use technologies?
Dual-use technologies have both commercial and government or national-security applications. Examples can include satellites, autonomous systems, cybersecurity, communications and advanced sensors.
What are the biggest risks of investing in defense and space SPACs?
Key risks include valuation, dilution, redemption, government-contract dependence, procurement delays, technology failure, capital requirements, regulatory constraints and execution risk.
Investment Disclaimer
This article provides general informational content and does not constitute financial, investment, legal, tax or other professional advice.
Investments in defense, aerospace, space technology, private companies, SPACs and newly public businesses can involve substantial risks, including volatility, dilution, redemption risk, government-contract dependence, regulatory changes, technology risk, capital requirements, execution risk and valuation uncertainty. Investors should conduct independent due diligence and consult qualified professional advisers.
Ana Goldenberg is a Contributing Editor at Alt Finances with a career rooted in the high-stakes worlds of banking and private placements. From profiling global philanthropists to managing complex financial operations at Wells Fargo, she bridges the gap between editorial storytelling and disciplined financial expertise.