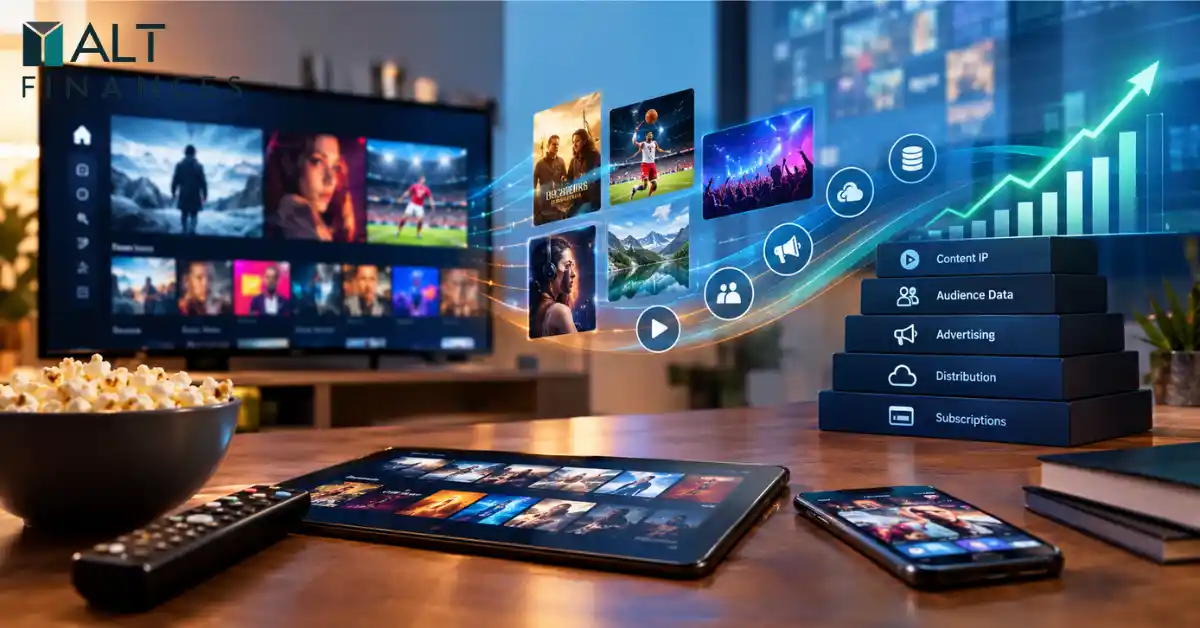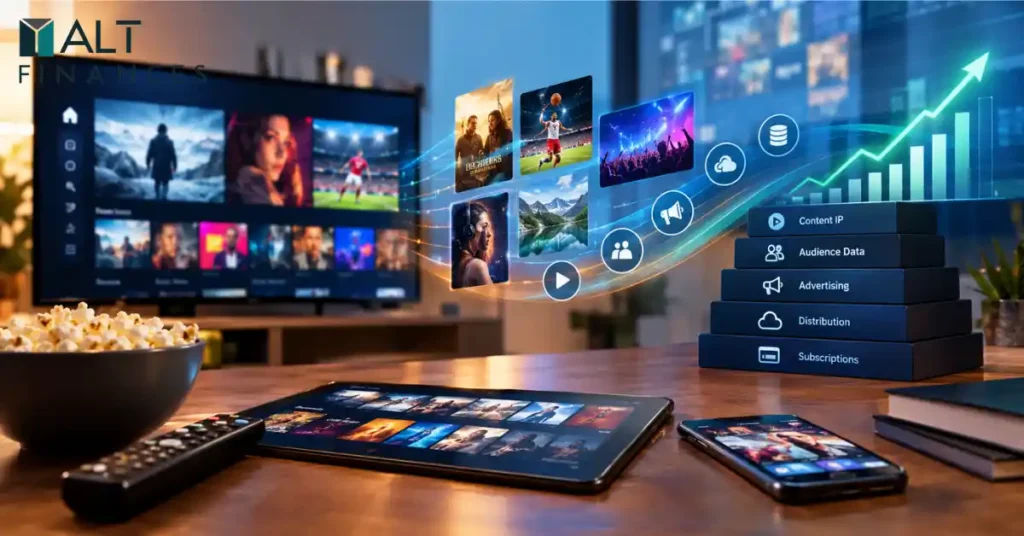
Streaming is no longer simply a technology for delivering entertainment. The business model has evolved into a combination of recurring subscriptions, advertising, intellectual property, audience data and multiple distribution channels. That shift is changing how investors can think about digital media businesses.
The distinction matters because a streaming company can generate value in several different ways. It may collect subscription revenue, sell advertising, license content, distribute channels, own valuable intellectual property or provide the technology that allows other media companies to monetize audiences.
The market is also moving away from the earlier assumption that subscriber growth alone determines success. In 2026, profitability, advertising monetization, content ownership, distribution scale and operating discipline have become increasingly important. PwC’s latest entertainment and media research says streaming revenue is still growing globally, but subscription fatigue is pushing platforms toward advertising, bundling and consolidation.
That creates a broader question for investors: What makes streaming businesses an investable digital asset rather than simply another media company?
Streaming Has Entered Its Profitability Era
The first generation of streaming was heavily focused on acquiring subscribers and expanding geographic reach. The economics are now more complicated.
A streaming platform can have millions of users and still face substantial costs for content, technology, marketing, licensing and distribution. Subscriber numbers therefore provide only part of the picture.
Investors increasingly need to examine the quality of the revenue generated by those users.
A subscription business has recurring revenue, but it also faces churn when customers cancel. A platform dependent on advertising has exposure to changes in ad demand and pricing. A company that owns content may have more control over its intellectual property but must also finance the production or acquisition of that content.
PwC’s 2026 global outlook projects OTT revenue to grow at a 6.1% compound annual rate through 2030, while noting that mature markets face subscription fatigue. It expects advertising to represent a larger share of OTT revenue as platforms expand ad-supported offerings.
This helps explain the industry’s changing priorities. Scale remains important, but scale without monetization is less useful than it once appeared.
For investors, the relevant question becomes whether a streaming audience can produce sustainable cash flow after content and operating costs.
Advertising Is Creating a Second Revenue Engine
Advertising is becoming an increasingly important part of streaming economics.
Three terms are particularly important:
- SVOD: Subscription Video on Demand, where customers pay for access.
- AVOD: Advertising Video on Demand, where content is primarily monetized through advertising.
- FAST: Free Ad-Supported Streaming Television, which generally provides scheduled or linear-style channels without a traditional subscription fee.
- CTV: Connected TV, referring broadly to television viewing delivered through internet-connected devices.
These models can overlap. A streaming platform might offer a subscription tier, a cheaper advertising-supported tier and free channels, giving it several ways to monetize the same audience.
The advertising opportunity is significant. The IAB projects U.S. digital video advertising spending will surpass $80 billion in 2026, with CTV, online video and social video all contributing to the market.
IAB — 2026 Digital Video Ad Spend & Strategy Report
Omdia’s 2026 research provides another useful perspective. It estimates that ad-supported CTV services could generate an average of $0.21 per viewing hour if available advertising inventory were fully sold. Omdia also found that the services it studied were operating at only about 65% of commercial advertising capacity.
That does not mean every streaming service can simply increase advertising revenue. Audience quality, viewing time, ad inventory, pricing, measurement and advertiser demand all matter.
But it demonstrates why advertising infrastructure has become strategically important.
Content Libraries Are Becoming Digital Assets
A streaming business is not necessarily valuable because it owns a large catalog. The more important question is what the content can generate over time.
A successful piece of intellectual property can potentially produce revenue through streaming, licensing, advertising, physical or theatrical distribution, gaming, merchandise and other channels.
Sports rights are another example. Live sports can create regular viewing occasions that are difficult to replicate with conventional library content, although rights can also require substantial financial commitments.
This makes content ownership different from simply having access to content.
A platform that licenses a program may benefit from its popularity, but the owner of the underlying rights may retain additional opportunities to license or distribute that intellectual property elsewhere.
The same principle appears outside traditional television. Music catalogs, for example, generate revenue from multiple digital channels.
AltFinances has previously examined this dynamic in Music Royalties: How Songs Have Become an Alternative Investment, where the underlying asset is the right to participate in future royalty income.
The broader investment lesson is similar: digital content can have economic value when ownership rights allow it to generate repeatable cash flows.
Why Streaming Businesses Are Attracting M&A Capital
Streaming consolidation is another indication that the industry is being evaluated increasingly through an economic rather than purely technological lens.
PwC’s June 2026 U.S. deals outlook describes the first half of 2026 as a period in which IP monetization and strategic consolidation became major themes in entertainment and media M&A.
PwC — Entertainment and Media: U.S. Deals 2026 Midyear Outlook
Scale can potentially improve the economics of a streaming operation by combining audiences, distribution relationships, advertising inventory, technology and content libraries.
But consolidation is not automatically value creating.
A larger company can also inherit expensive content commitments, overlapping technology systems, regulatory complications and organizational costs.
Private capital is similarly selective. PwC’s 2026 private-capital outlook describes a market where sponsors are concentrating capital in larger or more defensible opportunities rather than pursuing indiscriminate deal volume.
That distinction matters when evaluating streaming M&A. Investor interest does not establish that every streaming acquisition is economically attractive.
The Infrastructure Behind the Streaming Business
The investment opportunity also extends beyond the platform consumers see.
Streaming depends on a technological layer that includes content preparation, distribution, advertising technology, analytics, data and monetization systems.
A February 2026 transaction involving Cineverse illustrates this shift. Cineverse acquired CTV monetization company IndiCue for $22 million, combining its advertising technology with Cineverse’s Matchpoint platform. SEC filings describe IndiCue as a platform serving media owners, publishers and streaming operators and note that the transaction was intended to expand CTV monetization capabilities.
This is significant because it demonstrates a different type of streaming asset.
The business does not need to own the consumer-facing streaming service to participate in streaming economics. Technology that helps publishers distribute content, sell advertising, measure audiences or optimize monetization can itself become an acquisition target.
That creates three broad layers:
Content layer → Distribution layer → Monetization/technology layer
Different companies can capture value at different points in that chain.
Streaming Is Becoming a Digital Asset Stack
The most useful way to understand the sector may be as a digital asset stack rather than a single business model.
| Streaming Model | Primary Revenue | Key Asset | Major Risk |
|---|---|---|---|
| SVOD | Subscriptions | Audience and content | Churn |
| AVOD | Advertising | Audience and data | Ad demand |
| FAST | Advertising | Content library and channels | Monetization |
| Hybrid | Subscriptions + advertising | Platform, audience and IP | Cost complexity |
The distinction between owning content, distribution and technology is particularly important.
A content owner controls intellectual property.
A distribution platform controls access to audiences.
An advertising or technology company may control part of the monetization process.
A vertically integrated business can combine several of these layers, but it also takes on the costs and risks associated with each one.
This is why audience size alone is a weak measure of investment value.
A smaller platform with strong IP ownership, efficient customer acquisition and diversified monetization can have very different economics from a much larger platform that depends heavily on expensive licensed content.
What Investors Need to Examine
Anyone evaluating streaming businesses needs to look beyond subscriber or viewer numbers.
Revenue quality: How much revenue is recurring, contractual or dependent on advertising conditions?
Churn: How frequently do subscribers leave, and how much does the company spend replacing them?
Customer acquisition: What does it cost to acquire and retain an audience?
Content economics: Does the company own important IP or primarily license it?
Advertising exposure: How dependent is revenue on ad pricing, inventory and broader economic conditions?
Free cash flow: Does reported growth translate into cash after content and operating expenditure?
Distribution: Does the company control its distribution or depend on third-party platforms?
Technology: Is its infrastructure proprietary, scalable and economically efficient?
Valuation: How much future growth is already reflected in the price paid for the business?
These questions are especially important because streaming profitability can be affected by large upfront investments in content and technology.
The Risks Behind the Investment Thesis
Streaming businesses face several structural risks.
Content costs can remain high, particularly for premium entertainment and live sports.
Subscriber churn can weaken recurring revenue when customers have many competing services.
Advertising volatility can affect AVOD and FAST businesses when marketers reduce spending or demand better measurement.
Platform competition can make customer acquisition expensive.
Technology costs can rise as services expand their infrastructure and data requirements.
Regulation can affect advertising, content distribution, privacy and ownership structures.
And valuation risk remains important. A business can have a growing audience and still produce poor investment results if investors pay too much for that growth.
There is also a fundamental difference between owning a digital audience and owning an economic asset capable of producing durable cash flow.
That distinction should remain central to the analysis.
Conclusion
Streaming businesses are becoming more interesting from an investment perspective because the economics now extend well beyond subscriptions.
The sector combines recurring revenue, advertising, content IP, audience data, distribution networks and technology infrastructure. FAST and AVOD models are expanding the ways audiences can be monetized, while consolidation is encouraging companies to pursue greater scale and more efficient economics.
At the same time, streaming remains a capital-intensive and competitive industry.
The most useful investment question is therefore not which streaming platform has the most viewers.
It is which businesses can convert audiences, intellectual property and distribution into durable cash flow while maintaining disciplined costs and defensible economics.
That may include a subscription platform, a content owner, a CTV advertising business or a technology provider operating behind the scenes.
In that sense, the emerging digital investment frontier is not streaming alone. It is the collection of assets that sit underneath the streaming economy: content, audiences, distribution, data and monetization infrastructure.
Frequently Asked Questions
Why are streaming businesses attracting investors?
Streaming businesses combine several potential revenue sources, including subscriptions, advertising, licensing and content monetization. The investment case depends on whether those revenues can translate into sustainable cash flow.
How do streaming companies make money?
They can generate revenue through subscriptions, advertising, licensing, content distribution, partnerships and other digital services. Different companies rely on different combinations.
What is the difference between SVOD, AVOD and FAST?
SVOD primarily charges subscribers. AVOD provides video supported by advertising. FAST generally provides free, scheduled-style streaming channels funded primarily by advertising. Many modern platforms use hybrid models.
Why is streaming M&A increasing?
Scale, content ownership, advertising reach, distribution and technology can provide strategic reasons for consolidation. However, acquisitions also bring integration costs, content obligations and regulatory risks.
What risks should investors consider when evaluating streaming businesses?
Important risks include subscriber churn, content costs, advertising volatility, competition, technology spending, regulation, capital requirements and valuation. Audience growth alone does not establish investment attractiveness.
Investment Disclaimer
This article is provided for informational and educational purposes only and does not constitute investment, financial, tax or legal advice. Streaming businesses involve commercial, market and financial risks, and investors should conduct independent research and consult qualified professional advisers before making investment decisions.
Ana Goldenberg is a Contributing Editor at Alt Finances with a career rooted in the high-stakes worlds of banking and private placements. From profiling global philanthropists to managing complex financial operations at Wells Fargo, she bridges the gap between editorial storytelling and disciplined financial expertise.