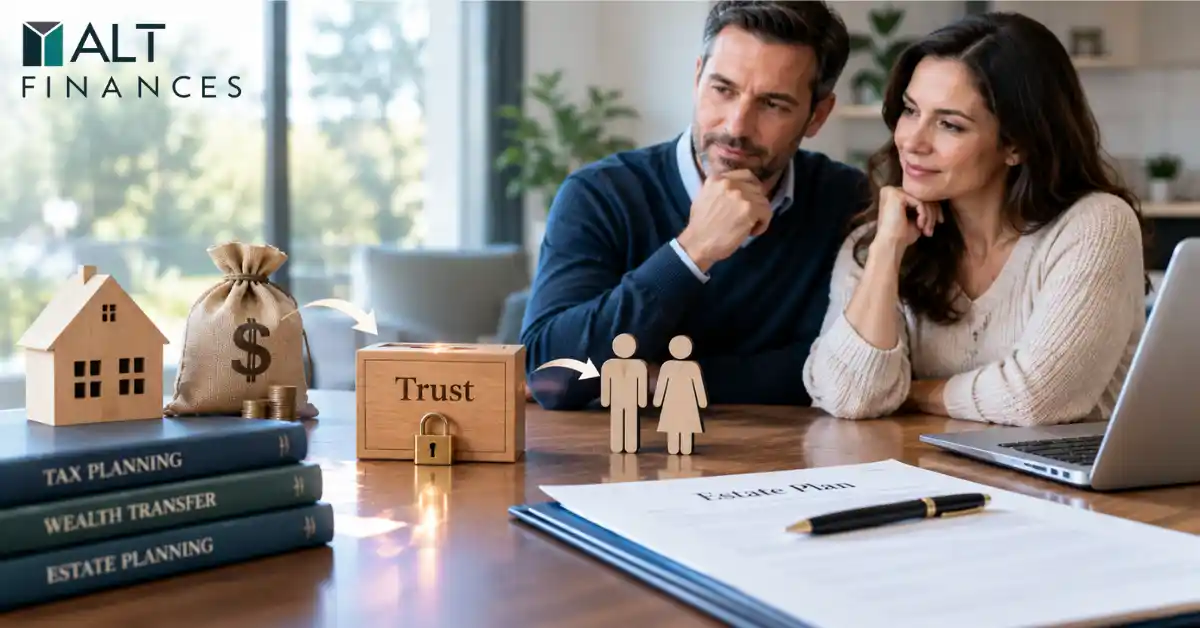
A married couple can transfer wealth during life and still preserve a degree of financial flexibility for the family. That combination is one reason Spousal Lifetime Access Trusts, commonly called SLATs, remain an important estate-planning strategy.
For 2026, the federal estate-tax basic exclusion amount is $15 million per person. That means many families will not face federal estate tax, but larger estates can still have substantial exposure, particularly when business interests, investment portfolios, real estate and future asset growth are considered.
A SLAT can potentially move assets outside the donor spouse’s taxable estate while allowing the beneficiary spouse to receive distributions under the trust terms. The strategy therefore sits at the intersection of estate-tax planning, lifetime financial access and long-term family wealth transfer.
But a SLAT is not simply a way to “remove assets and keep them.” Once assets are transferred to an irrevocable trust, the donor gives up significant control. The structure also creates risks involving divorce, the death of the beneficiary spouse, trust administration and reciprocal-trust rules.
What Is a Spousal Lifetime Access Trust?
A SLAT is generally an irrevocable trust established by one spouse for the benefit of the other spouse and, depending on its design, other family members.
The donor spouse transfers assets to the trust. The beneficiary spouse may then receive distributions according to the trust agreement.
The central estate-planning objective is that properly structured assets transferred to the SLAT, together with their subsequent appreciation, may not be included in the donor’s taxable estate.
The American Bar Association describes SLATs as trusts that can provide spousal access to distributions while supporting estate-planning objectives.
The key word is properly. A SLAT does not automatically remove assets from an estate simply because the document is called a SLAT.
The trust terms, transferred assets, powers retained by the donor, beneficiary rights and surrounding circumstances all matter.
Why Couples Consider SLATs
The main attraction is the ability to make a completed lifetime transfer while retaining an indirect source of financial flexibility through the beneficiary spouse.
Consider a simplified example.
Suppose one spouse owns $10 million of investments that are expected to appreciate significantly. The spouse could transfer qualifying assets to a properly structured SLAT for the other spouse.
If the transfer is completed successfully for federal gift and estate-tax purposes, future appreciation on those assets may occur outside the donor’s taxable estate.
Meanwhile, the beneficiary spouse may receive distributions when permitted by the trust.
This creates a potential combination of:
Lifetime Gifting + Estate Reduction + Spousal Access + Future Appreciation Outside the Estate
The strategy is particularly relevant when a family expects its assets to grow substantially over time.
However, the transfer is not reversible simply because circumstances later change.
The 2026 Estate-Tax Environment Matters
The federal basic exclusion amount for 2026 is $15 million per person. Married couples can potentially have access to two exclusions, subject to the applicable rules and planning. The IRS also permits portability of a deceased spouse’s unused exclusion when the required estate-tax return and election are properly handled.
That higher exclusion does not make SLAT planning irrelevant.
A family may currently be below the federal threshold but expect significant future growth from:
- A closely held business
- Private-company shares
- Real estate
- Investment portfolios
- Concentrated stock positions
- Carried interests
- Other appreciating assets
Estate planning therefore has to consider not only today’s balance sheet but also potential future appreciation.
A SLAT can be one tool for addressing that future exposure.
The Trade-Off: Access Comes With Limits
The biggest misconception about SLATs is that the donor spouse continues to own the assets while receiving all the same benefits.
That is not the point.
The donor spouse generally gives the assets away. Access is instead created indirectly through the beneficiary spouse.
This distinction matters.
If the beneficiary spouse receives distributions from the trust, those assets may be available for household expenses depending on the trust terms and applicable law. But the donor spouse cannot simply demand that trust assets be returned.
That means families should determine how much wealth can realistically be transferred without compromising their financial security.
A poorly sized transfer can create a practical problem even if the tax planning works exactly as intended.
The Irrevocable Nature of the Strategy
SLATs are generally irrevocable.
Once assets are transferred, the donor should not assume that the trust can later be cancelled or rewritten whenever circumstances change.
This makes liquidity planning especially important.
Before funding a SLAT, a family should consider:
How much wealth is needed to maintain the couple’s lifestyle?
What happens if investment returns disappoint?
What happens if one spouse develops significant care needs?
What happens if the couple divorces?
What happens if the beneficiary spouse dies first?
These questions can be more important than the initial tax calculation.
The Reciprocal Trust Problem
Couples sometimes consider creating two SLATs: one funded by each spouse for the benefit of the other.
This can appear attractive because both spouses may want to transfer assets outside their respective estates while preserving access through the other spouse.
But creating substantially similar trusts can create a reciprocal trust problem.
Under the reciprocal trust doctrine, courts can potentially treat formally separate trusts as effectively equivalent arrangements if the trusts are sufficiently interrelated. The result can undermine the intended estate-tax treatment.
Estate-planning professionals therefore pay close attention to differences in trust terms, trustees, beneficiaries, funding assets and other facts when two spousal trusts are contemplated.
There is no simple formula that makes two trusts automatically safe from reciprocal-trust concerns.
This is one reason SLAT planning requires individualized legal drafting rather than a template document.
Choosing the Assets to Transfer
The assets placed into a SLAT can significantly influence the economics of the strategy.
A family might consider assets with substantial appreciation potential, such as:
- Closely held business interests
- Investment portfolios
- Real estate interests
- Private-company equity
- Other assets expected to appreciate
The basic planning logic is straightforward:
Transfer Asset → Remove Future Appreciation From Donor’s Estate → Preserve Permitted Spousal Access
But valuation and tax consequences can become complex when assets are difficult to value.
A private-company interest, for example, can involve questions about valuation, transfer restrictions, minority interests and future liquidity.
The asset-selection decision therefore should not be separated from the family’s broader investment and liquidity plan.
SLATs and Business Owners
SLAT planning can be particularly relevant to founders and owners of closely held companies.
A business may be worth $5 million today and substantially more after another decade of growth. Waiting until a future liquidity event to consider estate planning could leave fewer options.
A properly structured lifetime transfer of an eligible business interest can potentially shift future appreciation outside the donor’s estate.
But business owners must consider operating agreements, shareholder restrictions, valuation requirements and control issues before transferring an ownership interest.
The tax strategy should not be allowed to interfere with the company’s ability to operate or raise capital.
What Happens If the Beneficiary Spouse Dies?
This is another critical issue.
The donor spouse may have expected the SLAT to provide financial flexibility throughout both spouses’ lifetimes. If the beneficiary spouse dies first, however, the donor’s indirect access may change or disappear depending on the trust design.
The trust might continue for children or other beneficiaries rather than returning the assets to the donor.
That possibility should be understood before the trust is funded.
Estate planning should therefore consider both possible orders of death rather than assuming the donor spouse will survive.
The Investor’s SLAT Checklist
Before establishing a SLAT, families should examine:
- Estate size — Is federal or state estate-tax exposure a realistic concern?
- Future appreciation — Which assets could grow substantially?
- Liquidity — Can the family comfortably live without the transferred assets?
- Trust terms — What distributions can the beneficiary spouse receive?
- Trustee — Who will control distributions and administration?
- Asset valuation — How will transferred assets be valued?
- Business restrictions — Are there limitations on transferring private-company interests?
- Reciprocal trusts — Are both spouses considering similar trusts?
- Divorce risk — What happens to the beneficiary’s interest?
- Death of the beneficiary spouse — Where do the assets go next?
- State law — Could state estate or inheritance taxes change the analysis?
- Documentation — Has the transfer been properly documented and reported?
These questions demonstrate why a SLAT is more than a tax document. It is a long-term wealth-ownership decision.
The Real Value of a SLAT Is Flexibility With a Price
The deeper point of Spousal Lifetime Access Trusts is not simply that they can reduce estate-tax exposure.
Their potential value comes from combining two objectives that normally pull in opposite directions:
Transfer Wealth Out of the Estate
and
Maintain Some Family Access to the Wealth
The trade-off is that the donor gives up direct ownership and control.
That means the strategy works best when families understand the difference between access and ownership.
A spouse may benefit from the trust without the donor spouse retaining unrestricted rights over its assets.
That distinction is central to the strategy.
Conclusion
A SLAT can be a powerful estate-planning tool for married couples with substantial wealth, particularly when assets are expected to appreciate significantly.
The 2026 federal estate-tax exclusion of $15 million per person means the strategy is not necessary for every household. But families with large or rapidly appreciating estates may have reasons to consider lifetime transfers before future growth increases their exposure.
The potential benefit is straightforward: assets and future appreciation may move outside the donor spouse’s taxable estate while the beneficiary spouse retains access to distributions permitted by the trust.
The cost is equally important: the transfer is generally irrevocable, direct control is reduced, and mistakes involving trust design, reciprocal arrangements, valuation or administration can undermine the intended result.
For that reason, the best way to evaluate a SLAT is not simply to ask how much estate tax it could save.
The better question is:
Can the family transfer enough wealth to achieve the planning objective while remaining financially comfortable if circumstances change?
That is where estate-tax planning becomes genuine wealth planning.
Frequently Asked Questions
What is a Spousal Lifetime Access Trust?
A Spousal Lifetime Access Trust, or SLAT, is generally an irrevocable trust created by one spouse for the benefit of the other spouse and potentially other family members. Properly structured transfers may remove assets and future appreciation from the donor’s taxable estate while permitting distributions to the beneficiary spouse under the trust terms.
Can a SLAT reduce estate taxes?
Potentially. Assets transferred through a properly structured SLAT may be outside the donor spouse’s taxable estate. The actual result depends on the trust terms, transfer, applicable tax rules and the family’s circumstances.
Can the donor spouse access SLAT assets?
Not directly in the same way as personally owned assets. The beneficiary spouse may receive permitted distributions, which can provide indirect household financial flexibility. The donor’s rights must be carefully limited to avoid undermining the intended tax treatment.
Can both spouses create SLATs?
Potentially, but creating substantially similar trusts for each other can raise reciprocal-trust concerns. The trusts should be independently designed with careful attention to their terms, funding and surrounding facts.
Is a SLAT still relevant with the 2026 estate-tax exemption?
It can be. The 2026 federal basic exclusion amount is $15 million per person, but families with substantial assets or significant expected appreciation may still face future estate-tax exposure. State estate taxes can also differ from federal rules.
Disclaimer
This article provides general informational content and does not constitute tax, legal, financial, estate-planning or investment advice. SLAT treatment depends on individual facts, trust language, applicable federal and state law, asset ownership and other circumstances. Anyone considering a SLAT should consult qualified estate-planning and tax professionals before transferring assets.
Marcie Bilawsky
Marcie Bilawsky is a Financial Writer & Research Contributor at AltFinances, covering investing, alternative assets, wealth management, and global financial markets. Her work focuses on making complex financial trends, investment themes, and emerging market opportunities easier to understand through research-driven analysis.