Private markets have created an unusual liquidity problem: investors can own valuable portfolios of private equity, private credit and other fund interests while still struggling to turn those assets into cash without selling them.
That tension is helping collateralized fund obligations, or CFOs, gain attention. Rather than immediately selling a portfolio of private-market interests, a CFO can place those interests into a structured vehicle and raise financing against them. The resulting securities divide the portfolio’s cash flows and risks among investors with different levels of seniority.
The market remains specialized and highly bespoke, but its scale is increasing. Dechert says market participants estimated annual CFO issuance at US$20 billion to US$25 billion in 2025, with some projecting approximately US$30 billion in 2026. Those figures are market estimates rather than definitive industry totals.
The significance of CFOs is therefore broader than another private-equity financing technique. They represent an evolving piece of structured finance that attempts to connect illiquid private assets with institutional fixed-income capital.
What Is a Collateralized Fund Obligation?
A CFO is essentially a structured vehicle that pools interests in private-market funds and finances them through different layers of securities.
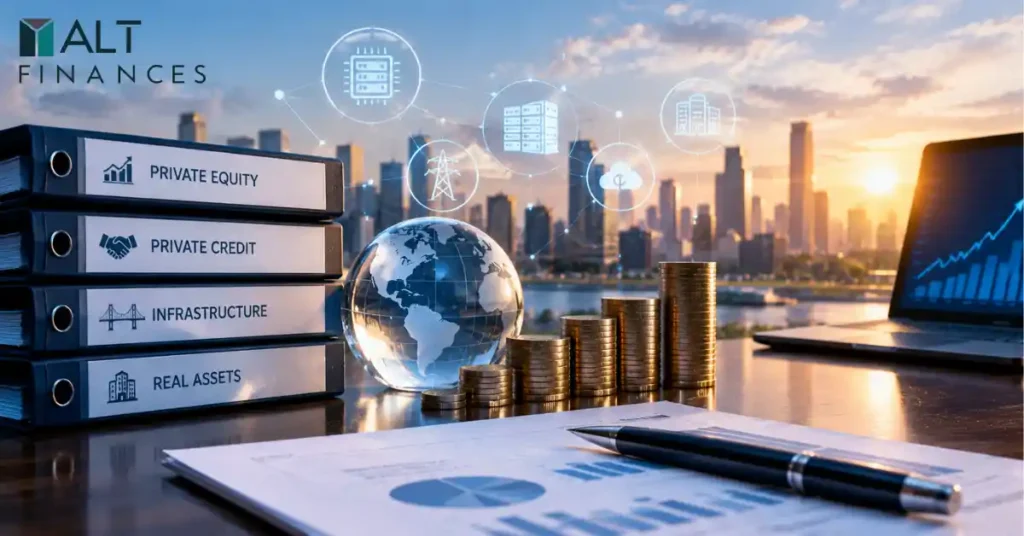
A typical structure involves a bankruptcy-remote special-purpose vehicle, or SPV, acquiring a diversified portfolio of fund interests. These can include limited partnership interests in private equity, private credit, infrastructure, secondaries and other strategies.
The SPV then issues securities backed by the portfolio.
At the top of the capital structure are senior notes. Below them may be subordinated or mezzanine securities, followed by an equity or residual tranche. Cash distributions from the underlying funds flow through a contractual waterfall, with senior claims generally receiving priority over junior claims.
Mayer Brown describes CFOs as vehicles in which pooled investments are held through bankruptcy-remote entities and financed through rated notes and equity. The precise structure varies from transaction to transaction.
The basic economic chain is:
Private-market interests → SPV → securitization → tranching → institutional capital
That is what differentiates a CFO from simply borrowing against a single fund portfolio.
Why CFOs Are Growing Now
Several developments are reinforcing demand for this type of structure.
First, private markets have become large enough that investors increasingly need financing and liquidity solutions around existing portfolios.
Second, private-market assets often have long investment horizons. A limited partner may want liquidity before the underlying funds distribute capital or reach their final exits.
Third, private credit has become an increasingly important component of institutional portfolios. CFO structures can accommodate credit-oriented fund interests alongside other private-market exposures.
Fourth, insurance companies and other regulated investors are looking for structured exposure to private assets that can fit within their investment and capital frameworks.
Dechert notes that CFO collateral has expanded beyond traditional private-equity interests to include infrastructure, private credit, direct lending and other assets. It also highlights the increasing importance of rated note feeders alongside traditional CFOs.
A significant 2026 transaction illustrates the trend. Franklin Templeton announced the closing of a US$1.5 billion CFO in August 2026, combining exposure to private-equity secondaries, continuation vehicles and U.S. middle-market direct lending across multiple vintages.
How Investors Are Financing Private-Market Portfolios
The key feature of a CFO is that investors do not all take the same risk.
Senior-note investors have a higher priority claim on the portfolio’s available cash flows. Their return is therefore more closely linked to the ability of the underlying assets to generate sufficient distributions and maintain the structural protections supporting the notes.
Equity investors sit at the bottom of the capital structure. They absorb losses before senior investors but can receive the residual economic upside after the higher-ranking claims have been satisfied.
This creates fundamentally different investment profiles even though every tranche ultimately depends on the same underlying portfolio.
Diversification can provide another layer of protection. A CFO may spread exposure across managers, investment strategies, geographies and fund vintages. But diversification does not eliminate private-market risk.
The quality of the underlying managers remains critical.
So do cash-flow timing, portfolio concentration, valuation methodology, leverage and the structure of the payment waterfall.
CFOs vs. NAV Lending and Secondary Sales
CFOs should not be confused with other private-market liquidity mechanisms.
CFO: A diversified portfolio of fund interests is placed into a structured vehicle that issues multiple layers of securities.
NAV lending: A borrower generally raises debt against the net asset value of an existing portfolio while retaining ownership of the underlying investments.
Secondary sale: An investor sells its existing private-market interests to another buyer, transferring ownership and receiving liquidity.
These structures solve different problems.
An investor using NAV lending is adding debt to an existing portfolio. An investor conducting a secondary sale is transferring assets. A CFO instead creates a financing structure around a pooled portfolio and allocates different levels of risk to different investors.
For a deeper look at portfolio-level borrowing, see NAV lending.
The distinction is important because financing liquidity is not the same as economic liquidity. A CFO can create securities that trade or are more readily held by institutional investors, but the underlying private assets can remain difficult to value and realize.
Why Insurance Companies and Institutional Investors Are Interested
The attraction for insurers and other institutional investors is partly structural.
A diversified pool of private-market interests can potentially be transformed into senior securities with defined contractual claims, credit enhancement and ratings.
That can create a more familiar fixed-income format than directly holding numerous private fund interests.
Insurance demand is particularly relevant because regulated investors often have to consider capital treatment alongside expected investment performance. Dechert notes that credit-oriented portfolios can be particularly relevant for structures designed around insurance investors’ requirements.
But a rating does not eliminate the risks of the underlying assets.
The rating addresses the credit characteristics of the specific security under an applicable methodology. It does not make private-company valuations certain, guarantee fund distributions or remove refinancing and structural risks.
That distinction should remain central to CFO underwriting.
The Risks Hidden Inside the Structure
CFOs create financing flexibility, but they also add complexity.
Valuation Risk
Private funds generally do not have continuously observable market prices. Valuations can change as portfolio-company performance, financing conditions and market multiples change.
Cash-Flow Risk
The CFO depends on distributions from underlying funds. Those distributions may arrive later than expected, creating pressure on debt service or liquidity.
Leverage and LTV Risk
A CFO can include loan-to-value tests and other structural triggers. If portfolio values decline, distributions to junior investors can be restricted or redirected toward senior claims.
Concentration Risk
A portfolio may appear diversified while still having meaningful exposure to particular managers, strategies, sectors, countries or vintages.
Manager Risk
The quality of the underlying general partners remains crucial. Weak investment performance can reduce distributions throughout the CFO structure.
Refinancing Risk
If debt matures before sufficient portfolio distributions have been received, the structure may need refinancing under less favorable market conditions.
Structural Complexity
Waterfalls, eligibility tests, concentration limits, valuation procedures, liquidity facilities and other contractual provisions can materially influence outcomes.
This is why CFO due diligence requires analysis of both the underlying assets and the financing architecture.
CFOs Turn Illiquidity Into a Financing Variable
The most important insight is that CFOs do not magically make private assets liquid.
They repackage the cash flows and risks of private-market holdings into securities with different claims and liquidity characteristics.
That changes the investment question.
It is no longer simply:
What are the underlying assets worth?
It becomes:
How are those assets financed, who bears the first losses, and when does cash actually reach each tranche?
This is where CFOs differ from a straightforward portfolio sale.
A secondary transaction monetizes an asset through a change in ownership. A CFO monetizes financing capacity while attempting to preserve the underlying portfolio’s long-term economics.
The structure can therefore create new capital without requiring the entire portfolio to be liquidated.
That potential is particularly relevant as private markets mature and investors look for more flexible ways to manage long-duration portfolios.
The Role of Private Credit
The expansion of private credit also matters to the CFO market.
Private-credit funds can provide predictable contractual cash flows compared with equity-heavy portfolios, although credit losses, borrower defaults, valuation changes and refinancing risks remain important.
Dechert’s 2026 market review notes that private-credit and direct-lending fund interests are becoming increasingly common CFO collateral.
For a CFO backed partly by credit-oriented assets, the investment analysis therefore extends beyond portfolio diversification. Investors must assess borrower quality, fund-level liquidity, manager underwriting and the timing of distributions.
The result is a structure that sits between private-market investing and institutional structured finance.
What Investors Should Examine
Investors assessing a CFO should look beyond the headline rating or expected financing cost.
The relevant questions include:
- What is the quality of the underlying fund portfolio?
- How diversified are managers, strategies, geographies and vintages?
- How reliable are expected distributions?
- How are NAV and LTV tests calculated?
- What protections do senior investors receive?
- How much subordinated capital absorbs initial losses?
- What valuation methodology is used?
- What fees and transaction costs reduce available cash?
- What happens if distributions are delayed?
- How easily can the structure be refinanced?
- Who controls the underlying portfolio and key decisions?
These considerations explain why two CFOs with similar ratings can still have materially different economic profiles.
What Comes Next for CFOs?
The CFO market is still evolving.
Dechert’s 2026 research describes CFOs as increasingly bespoke rather than standardized products, with new collateral types and structures emerging as investors and arrangers test what can be financed effectively.
The direction of travel is nevertheless clear.
Private-market portfolios are becoming financial assets around which multiple layers of financing, liquidity and risk transfer can be built.
That could make CFOs increasingly relevant to institutional investors seeking differentiated exposure to private assets without taking the same risk profile as direct LP ownership.
But growth also makes underwriting more important.
More financing flexibility means more structural complexity. More structural complexity means greater dependence on valuations, cash-flow timing, portfolio performance and legal documentation.
Conclusion
Collateralized fund obligations represent a significant evolution in private-market finance.
They allow portfolios of private fund interests to be pooled, financed and divided into securities with different levels of seniority. For sponsors and portfolio investors, this can provide an alternative to outright asset sales. For insurers and other institutional investors, it can create structured exposure to private-market cash flows.
The opportunity, however, is inseparable from the complexity.
CFOs depend on the quality of their underlying funds, the reliability of distributions, the accuracy of valuations and the protections built into their capital structures.
The market’s next phase will therefore depend less on whether CFO issuance grows and more on whether investors can accurately price the risks embedded beneath the structure.
For private markets, that may be the more important development: illiquidity is no longer simply a constraint. It is becoming a financing variable.
Frequently Asked Questions
What is a collateralized fund obligation?
A collateralized fund obligation is a structured-finance vehicle that pools private-market fund interests and finances them by issuing securities with different levels of seniority.
How do CFOs finance private-market portfolios?
An SPV or related structure holds a portfolio of fund interests and issues debt and equity securities. Cash distributions from the underlying investments are allocated through a contractual waterfall.
What is the difference between a CFO and a NAV loan?
A CFO generally securitizes a diversified portfolio through a structured vehicle with multiple investor tranches. A NAV loan typically provides borrowing against the value of an existing investment portfolio.
Who invests in collateralized fund obligations?
Investors can include insurers, institutional investors, private-market managers, family offices and other sophisticated investors, depending on the structure and regulatory requirements.
What are the biggest risks of CFOs?
Key risks include private-asset valuation uncertainty, leverage, delayed distributions, concentration, manager performance, structural subordination, refinancing risk, liquidity constraints and transaction complexity.
Investment Disclaimer
This article is for informational purposes only and does not constitute investment, financial, legal, tax or credit advice. CFOs and the underlying private-market investments can involve substantial risk, including loss of principal, illiquidity, valuation uncertainty, leverage and refinancing risk. Investors should conduct independent due diligence and consult qualified professional advisers before making investment decisions.
Ana Goldenberg is a Contributing Editor at Alt Finances with a career rooted in the high-stakes worlds of banking and private placements. From profiling global philanthropists to managing complex financial operations at Wells Fargo, she bridges the gap between editorial storytelling and disciplined financial expertise.