“20% carried interest” sounds simple. It is not.
An investor looking only at the headline carry percentage can miss some of the most important terms governing a private equity fund. The eventual economics can depend on the preferred return, catch-up provision, distribution waterfall, management fees, fund expenses, clawbacks and, importantly, when the general partner becomes entitled to carried interest.
That makes carried interest in private equity less a question of one percentage and more a question of fund structure.
Two funds can have similar headline carry rates but produce different cash-flow patterns and different net outcomes for limited partners because their waterfalls operate differently.
The distinction matters particularly when comparing private equity funds with different strategies, investment periods and distribution mechanisms. The governing limited partnership agreement, or LPA, ultimately determines the economics.
What Is Carried Interest in Private Equity?
Carried interest is a performance-based allocation of a private investment fund’s profits to the general partner or its affiliates.
It is different from the management fee.
Management fees generally compensate the manager for operating the fund and are typically calculated using a defined asset or commitment base. Carried interest, by contrast, is linked to investment performance and is generally earned only after specified conditions in the fund agreement have been satisfied.
The exact structure varies.
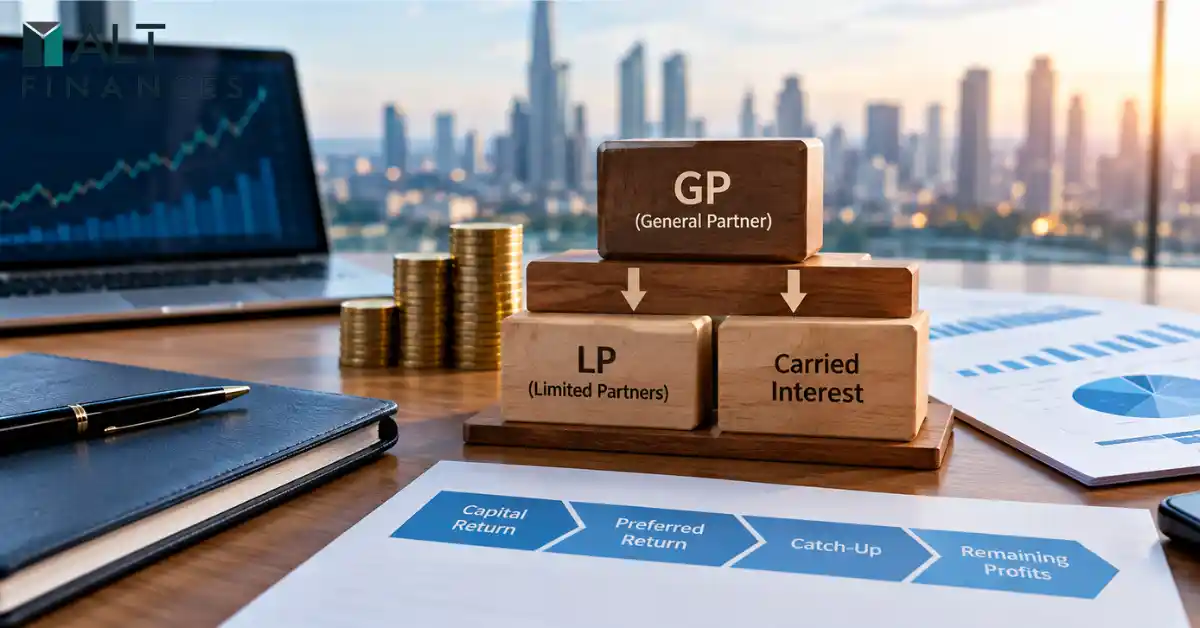
Some funds may use a preferred return before the GP receives performance compensation. A catch-up may then allocate a larger share of subsequent profits to the GP before the remaining profits are divided according to the agreed carry percentage.
The headline carry therefore tells only part of the story.
For U.S. taxpayers, there is also a separate tax consideration. Section 1061 generally requires certain holders of applicable partnership interests to satisfy a more-than-three-year holding period for relevant gains to receive long-term capital-gain treatment. The tax rules are separate from the fund’s contractual waterfall and should not be confused with it.
The Private Equity Waterfall Determines Who Gets Paid First
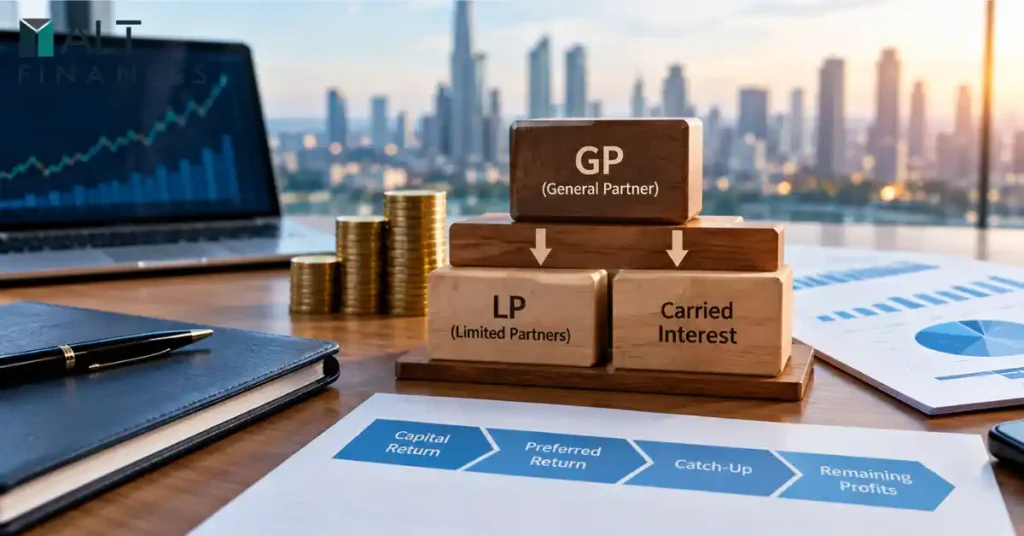
A private equity waterfall describes the sequence in which investment proceeds are distributed.
A simplified structure can look like this:
- Return of investors’ contributed capital.
- Payment of the applicable preferred return or hurdle.
- GP catch-up, if the fund agreement includes one.
- Remaining profits divided between LPs and the GP according to the agreed allocation.
The actual sequence can be considerably more complicated.
Some agreements calculate expenses, reserves, losses and other adjustments at different stages. Some include provisions for tax distributions. Others distinguish between realized and unrealized investments or impose additional conditions before carry can be distributed.
This is why the phrase “8% hurdle and 20% carry,” for example, does not by itself tell an investor what the final distribution will look like.
The SEC has specifically described the difference between whole-fund and deal-by-deal waterfalls in its private-fund rules. In a whole-fund structure, investors generally recover their relevant capital and preferred return across the fund before performance compensation begins. In a deal-by-deal structure, the GP can potentially receive carry earlier from successful investments.
American vs. European Waterfalls
The two broad structures most often discussed are American-style and European-style waterfalls.
A European-style waterfall generally operates at the fund level. The LPs typically receive distributions until the conditions covering contributed capital and the applicable preferred return have been satisfied across the relevant fund economics. Only then does carried interest begin to flow to the GP.
An American-style waterfall generally operates on a deal-by-deal basis, although actual agreements can contain modified versions.
When a successful investment is sold, the GP may become entitled to carry from that investment before every investment in the fund has been realized.
The timing difference is important.
Consider a hypothetical fund that makes several investments. One produces a substantial gain early in the fund’s life while two later investments perform poorly.
Under a whole-fund approach, the early gain may not generate the same immediate carry entitlement because the fund must first satisfy the applicable fund-level distribution requirements.
Under a deal-by-deal structure, the successful investment may generate carry earlier.
The SEC has noted that this can allow advisers to receive performance compensation earlier in the life of a fund, while also creating the possibility of a later clawback if final fund results do not support the amount previously distributed.
Why the Catch-Up Provision Matters
The catch-up is one of the easiest provisions to overlook.
Suppose a hypothetical fund has a preferred return and a 20% carried-interest allocation. Once the LPs have received the required capital and preferred return, the agreement may direct a large portion of subsequent profits to the GP until the GP has reached the agreed economic share.
After the catch-up is satisfied, remaining profits may then be divided according to the fund’s stated allocation.
The purpose is to establish the intended economics of the carried-interest arrangement after the hurdle has been achieved.
But catch-ups are not standardized.
Their percentage, starting point, duration and interaction with other provisions depend on the partnership agreement. Some funds also use different structures for different strategies or vehicles. That is why investors need to look beyond the headline carry rate and understand the private equity fund structure before evaluating potential net returns.
That makes the catch-up a term investors should examine rather than assume.
Clawbacks, Fees and the Other Terms Investors Need to Read
Carried interest can be distributed before the full investment portfolio has been liquidated.
That creates an important risk: later investments may perform poorly enough that the GP ultimately received more carry than it was entitled to retain under the final fund economics.
A clawback is designed to address that situation.
Current SEC filings provide real examples of why the provision matters. KKR disclosed in its March 2026 filing that carried interest previously distributed could become subject to clawback obligations if later investment performance reduced the GP’s ultimate entitlement. The filing reported approximately $195 million of carried interest subject to such an obligation under a stated liquidation-at-fair-value assumption as of March 31, 2026.
Carlyle’s March 2026 filing similarly describes carried interest as generally subject to preferred returns and catch-up provisions and notes that previously recognized carry may need to be returned if fund investment values subsequently decline.
Other terms matter as well.
Investors should examine management fees, fund expenses, fee offsets, organizational costs, transaction fees, reserves and the GP’s own capital commitment.
The difference between gross investment performance and the amount ultimately distributed to LPs can be material because the investor participates in the economics after the fund’s applicable expenses and allocations.
How Fund Structures Shape Investor Returns
Consider two hypothetical funds that each generate the same gross portfolio profit.
Fund A uses a whole-fund waterfall. The LPs must satisfy the relevant fund-level capital and preferred-return conditions before the GP receives carried interest.
Fund B uses a deal-by-deal waterfall. Several successful investments generate carry earlier, while weaker investments remain unrealized.
The underlying portfolio could eventually produce the same gross result in both funds.
The timing of cash flows, however, can differ substantially.
Fund B may distribute carried interest earlier. If subsequent investments disappoint, the GP may face a clawback depending on the agreement.
Fund A may delay the GP’s carry until more of the portfolio has been accounted for.
This does not make one structure universally better. It illustrates why investors need to compare the complete waterfall rather than relying on the carry percentage.
The relevant chain is:
Fund performance → distribution waterfall → GP carried interest → LP distributions → net investor return.
That is the economic pathway investors should understand.
The Investor’s Due-Diligence Checklist
When comparing private equity funds, investors should examine at least:
- Carry percentage: What percentage of eligible profits can the GP receive?
- Preferred return: Is there a hurdle, and how is it calculated?
- Catch-up: How does the GP catch up after the hurdle?
- Waterfall: Is it whole-fund, deal-by-deal or a modified structure?
- Timing: When can carry actually be distributed?
- Expenses: Which costs are charged to the fund?
- Fee offsets: Are transaction or monitoring fees credited against management fees?
- Clawback: Under what circumstances must previously distributed carry be returned?
- GP commitment: How much capital does the GP or its affiliates invest?
- Gross-to-net bridge: How do fees, expenses and performance allocations affect the LP’s final economics?
The comparison should also consider fund life, investment strategy and expected realization patterns.
A structure designed for a buyout fund may not be identical to one used for venture capital, private credit, infrastructure or other private-market strategies.
The Real Economics Are in the Partnership Agreement
The most important lesson is simple: carried interest in private equity is not adequately described by a single percentage.
The real economics sit inside the partnership agreement.
A 20% carry rate can interact with an 8% preferred return, a catch-up, management fees, fund expenses, a particular waterfall and a clawback in ways that are very different from another fund using the same headline carry.
Public disclosures demonstrate this variation. For example, Carlyle reported in its March 2026 filing that many of its closed-end carry funds generally had a 20% allocation after returning invested capital and preferred returns generally ranging from 7% to 9%, while also noting that terms vary across vehicles. Ares has likewise disclosed different carry and hurdle ranges across strategies. These are examples of actual fund structures, not universal private-equity standards.
For investors, that distinction is critical.
The appropriate comparison is not simply “20% versus 20%.”
It is the entire economic structure that determines when profits are shared, when carry is earned, how much cash reaches LPs and what happens if investment performance changes later.
Conclusion
Private equity fund economics are built from several interconnected terms.
Carried interest is important, but it is only one component. Preferred returns, catch-ups, waterfalls, fees, expenses, clawbacks and the timing of distributions can all influence the relationship between gross fund performance and net LP outcomes.
For that reason, investors evaluating private equity should look beyond the headline carry percentage.
The more useful question is how the entire fund structure converts investment performance into actual distributions.
That is where the economics of carried interest in private equity become clear.
Frequently Asked Questions
What is carried interest in private equity?
Carried interest is a performance-based allocation of a private investment fund’s profits to the GP or its affiliates. Its calculation and timing are governed by the fund’s partnership agreement.
How does a private equity waterfall work?
A waterfall establishes the order in which investment proceeds are distributed. A simplified version may return investor capital first, satisfy a preferred return, provide a GP catch-up and then divide remaining profits according to the agreed allocation.
What is the difference between American and European waterfalls?
An American-style waterfall generally permits carry to be calculated on a deal-by-deal basis, potentially allowing earlier carry distributions. A European-style waterfall generally applies the economics at the whole-fund level, typically delaying carry until specified fund-level return requirements are met.
What is a carried-interest clawback?
A clawback can require the GP to return previously distributed carried interest if later investment performance means the GP ultimately received more than it was entitled to under the fund agreement.
Investment Disclaimer
This article is for informational and educational purposes only and does not constitute investment, tax or legal advice. Private equity investments involve significant risks, including illiquidity, loss of capital, leverage, valuation uncertainty and complex fee structures. Actual fund economics are governed by the applicable partnership agreement and offering documents. Investors should conduct their own due diligence and consult qualified professional advisers.
Contributing Writer for Alt Finances with experience in luxury events, travel, fashion, and the arts. Active investor through her family office across real estate, energy, and private equity. University of Miami – BBA.