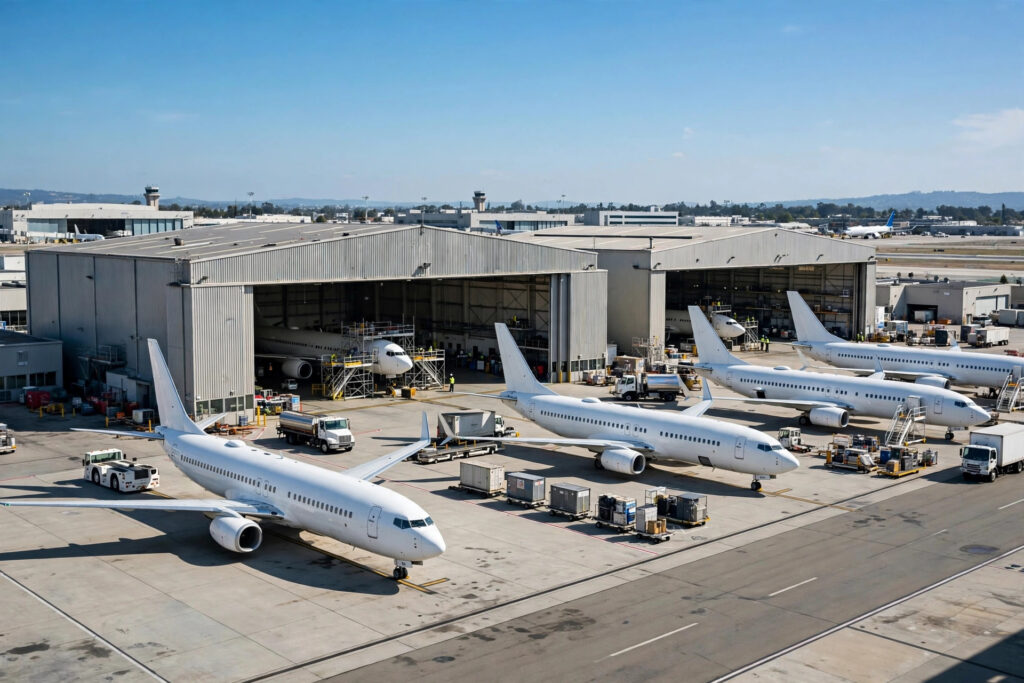
About half of the world’s commercial aircraft are not owned by the airlines flying them. They are leased, mostly from a handful of specialist lessors, in a market where the biggest player, AerCap, controls over $70 billion in assets. Aircraft leasing exists because airliners are absurdly expensive, airlines are cyclical, and flexibility is worth paying for.
Why half the world’s airliners are rented
Consider the maths from an airline’s seat. A new narrowbody jet costs roughly $50 to $60 million at typical discounted prices; a widebody can exceed $150 million. An airline growing its fleet by twenty aircraft is committing well over a billion dollars before hiring a single pilot. Buying outright ties up capital that could earn better returns elsewhere and leaves the airline holding an asset that loses value if travel demand slumps.
Leasing converts that capital commitment into a monthly bill. It also converts a fifteen-year bet on one aircraft type into an option: when the lease ends, hand the jet back and take a newer model. That flexibility has steadily won converts. AerCap, the industry’s largest lessor, reports that roughly 50% of the world’s commercial fleet is now leased, and that the fleet on operating lease has roughly trebled over the past twenty years. What began as a financing niche is now how half of global aviation gets its wings.
The three lease structures that matter
Operating leases are the industry’s workhorse: the lessor owns the aircraft and rents it to the airline for a fixed term, typically five to twelve years. The airline pays rent and covers operating costs; the lessor takes the residual-value risk at the end. Most of the leased fleet sits in this structure.
Finance leases work more like a hire-purchase agreement. The airline effectively buys the aircraft over the lease term and takes ownership at the end, bearing the residual-value risk itself. These suit airlines confident about an aircraft type’s long-term value.
Sale-leasebacks are the cleverest of the three. An airline orders aircraft from the manufacturer, then immediately sells them to a lessor and leases them back. The airline banks the cash difference between its order price and the sale price, which funds growth, while the lessor acquires a brand-new asset with a tenant already in place. In tight capital markets, sale-leasebacks are how airlines raise money without issuing debt.
How lessors actually make money
A lessor’s profit has three engines. The first is the spread between its funding cost and the lease rate: borrow cheaply in bond markets, lease expensively to airlines. Monthly lease rates for a new narrowbody run roughly $300,000 to $400,000 in current market conditions, varying with interest rates and aircraft scarcity.
The second engine is maintenance reserves. Lessees pay monthly reserves that build toward the cost of major overhauls, engines especially. If the aircraft returns in better condition than the reserves assumed, the lessor keeps the difference. Managing this well separates the great lessors from the mediocre ones.
The third is trading the aircraft itself. Lessors buy at scale, which wins discounts from manufacturers, then sell mid-life aircraft to other lessors, airlines or part-out specialists at prices reflecting their fleet-management skill. A lessor is part bank, part asset manager and part aircraft trader; the best ones are excellent at all three.
Why investors care about aircraft leasing
You cannot buy a single leased aircraft the way you buy a share, but the economics reach investors through several doors. The listed lessors, AerCap on the NYSE among them, offer direct equity exposure to the business model. Lessors also fund themselves through the bond market and through aviation asset-backed securities, where pools of aircraft leases are sliced into rated tranches for institutional buyers.
For individuals, the realistic exposure is through those listed equities or through funds holding aviation debt, not through owning metal. The return profile is distinctive: lease cash flows are contractual and long-dated, which cushions downturns, but the asset values are cyclical, which punishes mistimed buying. Aviation sits naturally alongside other alternative assets; our alternative finance guide places it in the wider non-traditional landscape, and our look at fractional aircraft ownership covers the private-aviation side of the same economics.
The risks, stated plainly
Aircraft leasing concentrates several risks that do not appear in ordinary corporate lending. Cyclicality is the first: when travel collapses, as it did in 2020, airlines defer deliveries, seek rent holidays and sometimes fail, leaving lessors with aircraft nobody wants. The survivors then benefit from the shortage, which is why the industry has historically recovered strongly, but the ride is violent.
Geopolitics is the second, and it stopped being theoretical in 2022. When sanctions followed Russia’s invasion of Ukraine, Western lessors lost access to hundreds of aircraft stranded in Russia. AerCap alone wrote off around $2.7 billion. Aircraft are mobile assets until a government decides they are not, and no lease clause fully insures against sovereign seizure.
Residual value is the third. A lessor betting on an aircraft type that later proves unpopular, think of models with checkered safety or efficiency records, eats the depreciation. This is why lessors obsess over “new technology” narrowbodies like the A320neo family and 737 MAX: over 90% of AerCap’s order book sits in that category, because those are the aircraft airlines will still want in a decade.
What the next few years look like
The industry’s near-term story is a supply squeeze. Aircraft manufacturers are delivering below their targets after years of supply-chain disruption, while air travel demand has recovered fully. Scarcity supports lease rates and aircraft values, which is good for lessors’ existing portfolios but makes fleet growth expensive.
Longer term, two forces dominate. Fleet renewal toward fuel-efficient aircraft will drive enormous capital spending, most of it lease-financed, because airlines cannot fund the transition from cash flow alone. And consolidation among lessors continues, as scale advantages in funding costs and manufacturer relationships compound. For anyone evaluating the sector, the question is not whether aviation needs lessors; it is which lessors have the balance sheet and the fleet mix to price risk correctly through the next downturn.
FAQ
How much does it cost to lease a commercial aircraft?
A new narrowbody such as an A320neo or 737 MAX leases for roughly $300,000 to $400,000 per month in current conditions, depending on interest rates, lease term and how scarce aircraft are. Widebodies cost several times more. Rates have risen notably since 2022 as higher interest rates lifted lessors’ funding costs.
Who are the biggest aircraft leasing companies?
AerCap is the largest by a distance, followed by Avolon, Air Lease Corporation, SMBC Aviation Capital and BOC Aviation. The top tier is concentrated: a handful of lessors control most of the leased fleet, which gives them pricing power with both manufacturers and airlines.
Why do airlines lease instead of buy?
Leasing preserves capital, keeps debt off the balance sheet under operating leases, and provides fleet flexibility: an airline can return aircraft at lease end rather than being stuck with an ageing fleet. For fast-growing carriers, sale-leasebacks also function as a funding source.
Can ordinary investors invest in aircraft leasing?
Directly owning leased aircraft is institutional territory, but listed lessors’ shares and funds holding aviation debt or asset-backed securities offer indirect exposure. Expect equity-like volatility with bond-like cash flows underneath; it is a hybrid exposure, and should be sized accordingly.
What happens to leased aircraft when an airline goes bankrupt?
The lessor repossesses the aircraft and seeks a new lessee, which is why standardised, in-demand aircraft types matter so much: an A320neo finds a new home quickly, while an oddball type can sit idle for months. Repossession across borders can get legally messy, which is why lessors price jurisdiction risk into every deal.
Sources
- AerCap fact sheet, as of December 31, 2025: ~$72 billion total assets; ~50% of the world’s commercial aircraft fleet leased; operating-lease fleet trebled in 20 years. aercap.com
- AltFinances, What Is Alternative Finance (AltFi)? The Complete 2026 Guide and Private Aviation as an Asset Class.
Administrator at Alt Finances, leading editorial strategy and contributing in-depth coverage of investing, wealth management, alternative assets, and global financial markets. Through research-driven articles and analysis, he helps readers understand the ideas, industries, and market forces shaping modern finance.