Everyday financial life involves a steady stream of decisions. You decide what to buy, which bills to pay first, whether to save more, how to manage debt, and whether an investment deserves attention. Individually, these choices may appear manageable. Together, they can compete for time, concentration and emotional energy, particularly when work, family responsibilities and financial uncertainty are already demanding.
This is where financial decision fatigue becomes a useful concept. It describes the difficulty people may experience when repeated or complicated financial choices become mentally exhausting. That exhaustion can contribute to procrastination, inconsistent habits or decisions made for immediate convenience rather than long-term benefit.
However, financial mistakes are not always psychological. Insufficient income, rising living costs, unexpected expenses and limited access to financial resources can leave people with difficult choices regardless of their level of discipline.
The more useful question is not how to eliminate every difficult decision. It is how to organize everyday financial responsibilities so that routine choices require less effort and important decisions receive the attention they deserve.
What Is Financial Decision Fatigue?
Financial decision fatigue refers to the perceived mental burden associated with making repeated or demanding money-related choices. It overlaps with broader concepts such as cognitive overload, stress and decision avoidance, but these experiences are not identical.
Cognitive overload occurs when the information or number of tasks exceeds what someone can comfortably process at a given time. Financial stress involves concern about obligations, uncertainty or the ability to meet future needs. Decision avoidance happens when a person delays or declines to make a choice.
These experiences can reinforce one another. Someone worried about outstanding bills may struggle to compare repayment options, postpone reviewing their accounts and feel more anxious as deadlines approach.
Psychological research also cautions against assuming that every decision uses up a fixed supply of willpower. Research into self-control and so-called ego depletion remains an evolving field, and individual responses vary. Financial decision fatigue is best treated as a useful way to understand certain patterns of behaviour, not as a universal explanation for financial mistakes.
How Everyday Money Choices Consume Attention
Modern financial life creates many opportunities to make decisions. Digital shopping, subscription services, contactless payments, promotional offers and frequent account notifications can make spending and account management convenient, but they also create repeated prompts to act.
Investment decisions can be demanding for a different reason. People may need to compare fees, understand risk, assess competing opinions and distinguish useful information from market speculation. When financial information is contradictory or overly technical, even a relatively straightforward choice can become difficult.
Consider a hypothetical example. Someone finishes a demanding workday, remembers an unpaid bill, receives a subscription renewal notification and notices an unexpected expense. They intend to review their savings plan but postpone it because dealing with the immediate tasks feels easier.
One postponed review does not necessarily damage their financial future. The concern arises when the same pattern repeatedly delays important tasks or makes financial management harder than it needs to be.
The objective is not to scrutinize every small purchase. It is to recognize when too many recurring decisions are competing for limited attention.
How Decision Fatigue Can Affect Long-Term Wealth
Long-term financial progress depends partly on repeated actions. Saving regularly, meeting obligations, reviewing spending and maintaining an appropriate investment plan all require some degree of consistency.
When financial responsibilities become overwhelming, people may delay reviewing their budgets, ignore account notifications, postpone decisions about expensive debt or make purchases simply to avoid further deliberation. Some investors may also react emotionally to market movements instead of following a considered plan.
These are possible behavioural patterns, not inevitable consequences of fatigue. A missed savings contribution may result from a genuine shortage of money, while an impulsive purchase may reflect social pressure, a poor spending plan or an unexpected need.
The distinction matters because the solution depends on the underlying problem. Simplifying a process may help someone who is overwhelmed by too many tasks. It cannot make an unaffordable budget affordable or eliminate the financial pressure created by inadequate income.
For readers working on their overall money management, a useful starting point is to review their existing financial planning strategy. A clear picture of income, expenses, obligations and goals can make individual decisions easier to place in context.
The Psychology Behind Financial Overload
Three behavioural factors help explain why financial choices can become difficult.
Present bias
Present bias describes the tendency to give immediate rewards or costs more weight than future consequences. A purchase today can feel more rewarding than the less visible benefit of saving for a future goal.
This does not mean people are naturally irresponsible. Immediate needs are often legitimate, and future outcomes may be uncertain. Problems can arise when short-term preferences repeatedly override priorities that matter more over time.
Information overload
More information does not always produce better decisions. Comparing numerous savings accounts, investment products or repayment strategies can become counterproductive when the differences are difficult to understand.
A person may spend hours researching minor details while postponing a more important decision. Establishing a reasonable set of criteria can help narrow the choices without pretending that every product is equivalent.
Stress and uncertainty
Financial stress can make it harder to concentrate on complex tasks. Someone concerned about job security or an unexpected expense may naturally prioritize immediate obligations over long-term planning.
The Consumer Financial Protection Bureau describes financial well-being in terms of day-to-day control, the capacity to absorb financial shocks, progress toward goals and freedom of choice. Its financial well-being framework is a useful reminder that financial security involves more than income or net worth.
These factors can interact, but no single explanation accounts for every financial decision. Personal circumstances, available resources and the quality of information all matter.
Simplifying Financial Decisions Without Losing Control
A practical financial system should reduce unnecessary effort while keeping important decisions visible.
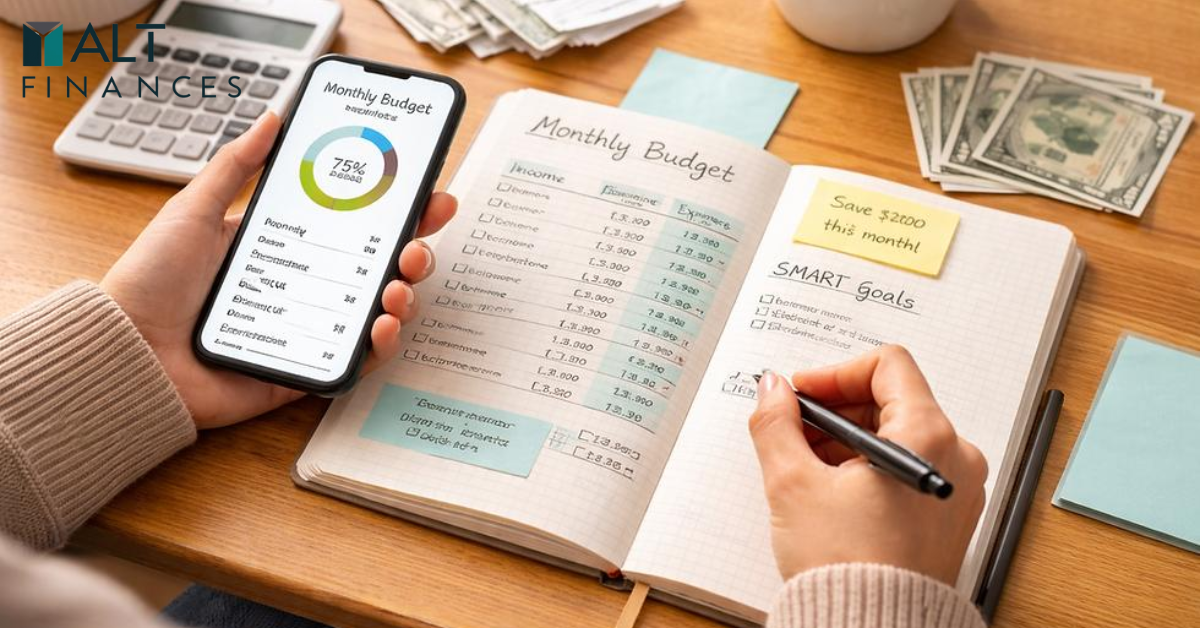
Establish a manageable spending plan. Group expenses into a few useful categories, such as essential costs, debt obligations, savings and discretionary spending. The plan should reflect actual income and living costs rather than an idealized budget that is difficult to maintain.
Automate suitable recurring tasks. Where appropriate, automatic bill payments and scheduled savings contributions can reduce the number of decisions that must be made each month. Before automating payments, check account balances, payment dates and possible overdraft fees. Review arrangements periodically, particularly when income or expenses change.
Reduce unnecessary notifications. Consider turning off promotional messages and nonessential financial alerts. Retain notifications that help identify unusual transactions, missed payments or important account changes.
Create a regular review schedule. A short weekly check of upcoming expenses and a more detailed monthly review may help keep responsibilities manageable. The frequency should suit the complexity of the person’s finances.
Set rules for routine purchases. A planned spending limit or a short waiting period before nonessential purchases can create space for reflection. However, rigid rules should not prevent necessary spending or make ordinary financial decisions unnecessarily stressful.
Keep major decisions separate. Borrowing significant amounts, changing an investment allocation or committing to a long-term financial obligation deserves more careful evaluation than choosing an everyday purchase. Simplicity should not become a reason to rush consequential decisions.
Financial Decision Fatigue and Investment Behaviour
Investment decisions can be especially vulnerable to information overload because prices change, forecasts conflict and uncertainty cannot be eliminated.
Frequent portfolio checking may encourage some investors to respond to short-term movements rather than their goals, time horizon and ability to tolerate losses. Others may delay reviewing an investment because they find the information confusing or fear making the wrong choice.
A written investment plan can help establish which changes warrant attention. It might define the purpose of each investment, the intended time horizon, acceptable risk and circumstances that would justify a review.
A plan should not become an excuse to ignore new information. Changes in income, financial obligations, risk tolerance or investment fundamentals may justify reassessment. The aim is to avoid reacting to every fluctuation while remaining willing to act when circumstances genuinely change.
Investors who need money within a relatively short period should also consider how the timing of their goals affects the level of risk they can reasonably take. AltFinances explores this issue in its guide to short-term investments.
The broader principle is to make investment decisions deliberately, rather than allowing every headline or market notification to become a new decision point.
When Simplification Is Not Enough
Financial systems can help organize responsibilities, but they cannot resolve every financial difficulty.
A household facing high rent, expensive debt, unstable employment or medical bills may have very little flexibility. In such circumstances, the challenge may not be too many decisions but too few realistic options.
People dealing with persistent debt pressure may need to examine interest rates, minimum payments, essential expenses and available repayment arrangements. Where appropriate, reputable nonprofit debt-counselling services or qualified financial professionals may help them understand their options.
It is equally important to avoid blaming individuals for circumstances beyond their control. Better habits can support financial management, but they do not guarantee financial security.
Building a Financial System That Supports Better Decisions
A useful approach begins with a few practical steps:
- Identify recurring decisions. List the money-related tasks that repeatedly demand attention, including bills, subscriptions, debt payments and savings.
- Separate routine from consequential choices. Simplify predictable tasks while allowing more time for borrowing, investing and other significant commitments.
- Remove unnecessary complexity. Reduce redundant accounts, confusing categories and irrelevant notifications where doing so makes sense.
- Automate selectively. Use scheduled payments or savings transfers when they fit your cash flow, and maintain enough oversight to catch errors or changing circumstances.
- Review progress regularly. Choose a manageable schedule for checking balances, upcoming obligations and progress toward meaningful goals.
- Adjust when life changes. Revisit the system after changes in employment, income, family responsibilities or financial priorities.
The system should be simple enough to maintain and flexible enough to accommodate real life. If it requires constant monitoring or creates more anxiety than it removes, it may need to be redesigned.
Frequently Asked Questions
What is financial decision fatigue?
Financial decision fatigue describes the mental strain that may arise from repeated or complicated money decisions. It can contribute to postponement, inconsistent habits or reliance on convenient choices, although its effects differ among individuals.
Can decision fatigue affect spending and saving?
It may influence how people approach purchases, savings and financial tasks. However, income, living costs, debt and unexpected expenses also shape financial behaviour and should not be overlooked.
How can people reduce financial decision fatigue?
A manageable spending plan, selective automation, fewer unnecessary notifications and regular financial reviews may reduce avoidable effort. Important decisions should still receive careful attention.
Does financial decision fatigue affect investing?
Information overload and stress may influence how investors respond to market movements. A clear investment plan can provide structure, but it should be reviewed when goals, circumstances or relevant financial information change.
The Long-Term Value of Better-Structured Decisions
Building wealth is not simply a matter of making perfect decisions. It also involves creating a realistic way to handle recurring financial responsibilities without allowing every choice to become a source of unnecessary pressure.
Financial decision fatigue offers one lens for understanding why people sometimes postpone tasks or struggle to maintain consistent habits. It should not be used to explain every financial mistake or overlook the economic constraints that shape people’s choices.
The practical objective is to reserve attention for decisions that matter most. By simplifying routine tasks, reviewing financial commitments regularly and remaining flexible when circumstances change, individuals may find it easier to manage their money with greater consistency.
Disclaimer: This article is for informational and educational purposes only and does not constitute individualized financial or investment advice.
Administrator at Alt Finances, leading editorial strategy and contributing in-depth coverage of investing, wealth management, alternative assets, and global financial markets. Through research-driven articles and analysis, he helps readers understand the ideas, industries, and market forces shaping modern finance.