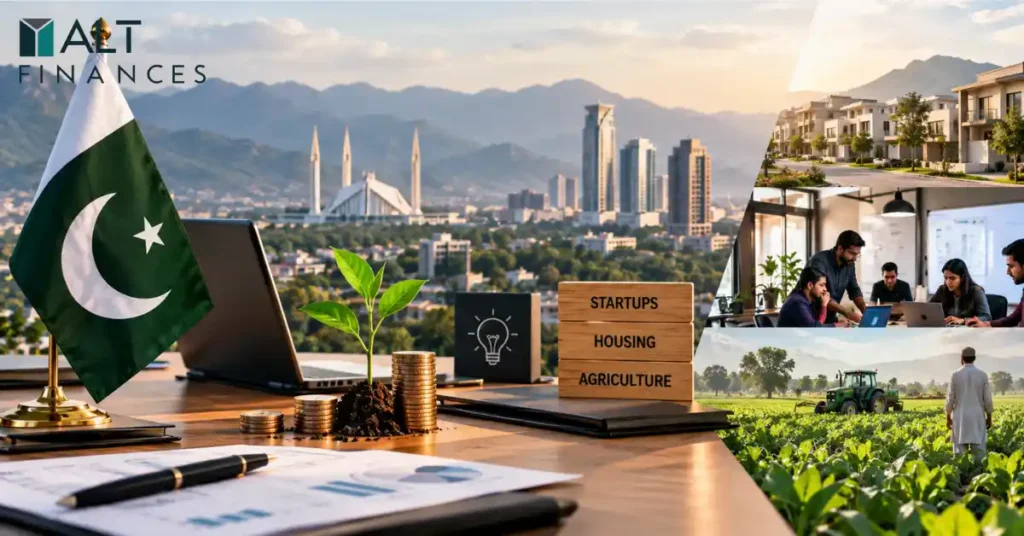
Pakistan’s financing system is entering a phase in which the question is no longer simply how much credit banks can provide, but how the country can bring more forms of private and institutional capital into productive sectors.
That shift is becoming visible in Islamabad. In 2026, the government has expanded its Access to Finance Plan across small and medium-sized businesses, agriculture, housing, exports and technology.Plan On October 6, the Finance Ministry and International Finance Corporation (IFC) also discussed an entrepreneur fund, affordable-housing developer finance, agricultural financing and mechanisms for mobilising private capital.
The important distinction is that these initiatives do not automatically represent new private investment. Some are policy proposals, some are financing approvals, and others are mechanisms intended to encourage investors to participate. The bigger question is whether Pakistan can build structures that make private capital comfortable enough with the risks to participate at scale.
Why Pakistan Is Looking Beyond Traditional Bank Lending
Traditional bank lending remains central to Pakistan’s financial system, but policymakers are trying to diversify the sources of capital available to businesses and households.
By the end of August 2026, SME financing had reached PKR 1.067 trillion, while agriculture finance stood at PKR 1.268 trillion, according to the Finance Division. The government has set higher medium-term targets, but those targets should not be confused with capital already deployed.
Housing provides another example. Under the Wazir-e-Azam Apna Ghar Programme, approved financing had reached PKR 351.3 billion by September 4, while actual disbursements were PKR 51.13 billion. The difference illustrates why investors should distinguish between applications, approvals and money that has actually reached borrowers.
The broader objective is therefore not to replace banks. It is to add financing channels that can provide equity, longer-term capital, risk-sharing and specialized lending.
Startups: Building a Bridge Between Government Support and Private Investors
Pakistan’s startup ecosystem has one important financing mechanism in the Pakistan Startup Fund.
The program can provide a non-equity grant of up to 30% of an eligible investment round, subject to its requirements, with private investment required or in advanced stages before the government contribution. The current program information lists grants between $50,000 and $1 million.
This structure is significant because it is designed to complement rather than replace private capital.
For a venture investor, the distinction matters. A government grant can reduce the amount of private capital required to complete a financing round, potentially changing the risk-sharing structure. But it does not remove the fundamental risks of venture investing: startup failure, weak governance, uncertain cash flows, difficult exits and valuation uncertainty.
Pakistan is also developing broader mechanisms for startup funding. SECP’s 2026 regulatory agenda includes proposals aimed at improving funding access for startups, while the wider capital-market reform program is seeking to deepen non-bank sources of financing.
For investors, the quality of the private capital ecosystem will ultimately depend on whether successful companies can raise successive rounds and eventually provide credible exit opportunities.
That makes startup secondary markets increasingly relevant to the wider ecosystem: investors need ways to realize value without relying exclusively on an IPO.
Housing: Can Developer Finance Unlock More Supply?
Housing illustrates a different problem.
Consumer mortgage finance helps households purchase homes, but housing supply also depends on developers obtaining suitable construction and development capital. That is why the October IFC discussions included potential developer-finance models designed to address supply-side constraints.
Pakistan has also been widening the role of non-bank financial companies in housing finance. SECP’s 2026 measures include the participation of lending NBFCs in government-backed affordable-housing financing and risk-coverage arrangements.
The investment ecosystem could eventually include banks, housing-finance companies, developers, REITs and other capital providers.
But more financing does not automatically mean better investment outcomes. Housing depends on land prices, construction costs, household affordability, interest rates, title quality, recovery mechanisms and developer execution.
For institutional investors, the key issue is therefore the quality and predictability of the underlying cash flows—not simply the size of the housing-finance program.
Agriculture: Turning Physical Assets Into Financeable Collateral
Agriculture presents an even more specialized financing challenge because many small farmers lack conventional collateral and operate within highly variable production cycles.
The IFC’s AgriConnect discussions in October focused on storage infrastructure and electronic warehouse receipts as potential collateral. The basic concept is straightforward: stored agricultural commodities can be documented electronically, allowing lenders to finance inventory rather than relying entirely on traditional property collateral.
This could connect agricultural producers, storage operators, lenders and buyers through a more structured financing chain.
The idea is not risk-free. Commodity prices can fall, stored goods can deteriorate, storage arrangements can fail and borrowers can still default. But better collateral documentation and stronger supply-chain infrastructure could potentially improve lenders’ ability to assess and manage those risks.
That makes asset-backed finance relevant beyond conventional consumer or corporate lending. In agriculture, the underlying commodity and its documented value can become part of the financing structure.
The Private-Equity Push: Why Alternative Capital Matters
Perhaps the most important structural development is Pakistan’s effort to build a broader private-equity ecosystem.
In September 2026, the Finance Ministry said a National Private Equity Policy Framework was being developed to mobilize domestic and international long-term capital. Discussions included regulatory treatment, taxation, institutional participation, valuation, investor exits and safeguards against misuse.
Private equity is different from bank lending. A bank generally expects contractual repayment and interest. A private-equity investor purchases an ownership interest and accepts business risk in exchange for potential capital appreciation.
It is also different from venture capital. Venture capital generally focuses on earlier-stage, high-growth companies, while private equity can target more mature businesses, expansion opportunities or ownership transitions.
For Pakistan, the policy challenge is not simply creating another investment vehicle. It is creating the conditions under which pension funds, insurers, banks, development-finance institutions, family offices and international investors can commit capital with greater clarity around regulation, taxation, valuation and exit routes.
What Could Prevent Private Capital From Scaling?
The obstacles are substantial.
Currency risk matters to international investors because returns generated in Pakistani rupees can change materially when converted into foreign currency.
Regulatory uncertainty can raise the required return on an investment or discourage long-duration commitments.
Exit risk is equally important. Equity investors need credible routes to sell their holdings through strategic sales, secondary transactions or public markets.
Corporate governance and information quality affect how investors assess private businesses. Weak reporting can make valuation and due diligence more difficult.
Credit and recovery risk remain important for lenders, particularly where collateral enforcement is slow or uncertain.
Finally, Pakistan’s financing ecosystem remains exposed to broader macroeconomic and political conditions. Private capital is generally more comfortable when rules are predictable, contracts are enforceable and investors understand how capital can enter, operate and eventually exit.
Pakistan Is Trying to Build a Capital-Mobilization Machine
The most interesting part of Pakistan’s 2026 financing agenda may therefore be the architecture rather than any single fund or lending program.
The government is trying to connect policy reform, development finance, banks, NBFCs, capital markets, private equity, venture capital and institutional investors.
That is different from simply increasing government lending.
The Pakistan Startup Fund, for example, is explicitly structured around private investment participation. The IFC discussions similarly focus on mechanisms that could mobilize private financing rather than simply provide public-sector loans.
The same principle can apply to housing and agriculture: government guarantees, risk-sharing, better collateral systems or regulatory reforms can potentially reduce barriers that previously made certain transactions difficult to finance.
But the test is ultimately measurable.
If programs produce announcements without sustained private participation, the ecosystem will remain dependent on public intervention. If reforms create investable businesses, reliable collateral, credible cash flows and workable exits, private capital can become a more durable source of financing.
Conclusion
Pakistan’s private capital push is still a developing ecosystem rather than a completed investment market.
The 2026 developments show a clear policy direction: broaden financing beyond traditional bank credit, strengthen startup funding, expand housing finance, improve agricultural collateral and create a more credible private-equity framework.
The central question is whether those mechanisms can crowd in genuine private capital without simply transferring existing credit, currency or execution risks to investors or the public sector.
That outcome will depend less on the number of funding announcements and more on the fundamentals underneath them: transparent regulation, credible valuations, enforceable contracts, reliable cash flows, functioning capital markets and realistic exit opportunities.
For Pakistan private capital to scale sustainably, those foundations matter more than any individual financing program.
Frequently Asked Questions
What is Pakistan’s private capital push?
It is the broader effort to expand financing beyond traditional bank lending by encouraging venture capital, private equity, institutional investment, non-bank finance and other forms of private-sector funding.
How is Pakistan trying to finance startups?
The Pakistan Startup Fund can provide eligible startups with non-equity grants of up to 30% of an investment round, subject to program conditions and private-investment participation.
How is Pakistan expanding housing finance?
The government is expanding affordable housing finance while SECP has enabled greater participation by lending NBFCs and is working on reforms affecting the housing and REIT sectors.
How could agriculture attract more private capital?
Mechanisms such as storage infrastructure, electronic warehouse receipts and risk-sharing arrangements could make agricultural assets and inventories easier for lenders to evaluate and finance.
What role could private equity play?
Private equity can provide ownership capital to businesses rather than contractual debt. Pakistan’s proposed policy framework aims to make the ecosystem more transparent and attractive to domestic and international long-term investors.
What are the biggest risks?
Currency, regulatory, credit, liquidity, governance, political and exit risks remain important. Government programs can reduce some barriers, but they cannot eliminate investment risk.
Does announced financing mean capital has already been invested?
No. Applications, approvals, commitments and actual disbursements are different stages. Investors should examine deployed capital rather than relying solely on headline program targets.
Investment Disclaimer: This article is for informational and educational purposes only and does not constitute investment, legal or financial advice. Investment outcomes depend on individual circumstances, market conditions, regulatory developments and risk tolerance.
Administrator at Alt Finances, leading editorial strategy and contributing in-depth coverage of investing, wealth management, alternative assets, and global financial markets. Through research-driven articles and analysis, he helps readers understand the ideas, industries, and market forces shaping modern finance.