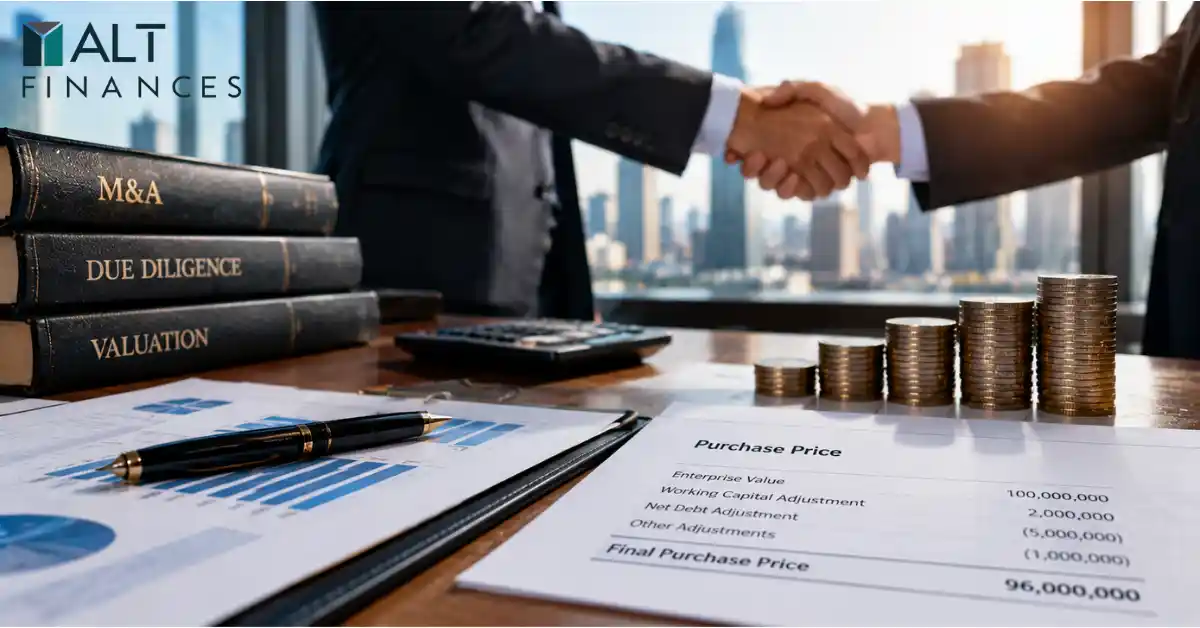
In an M&A transaction, the headline purchase price can look definitive long before the deal actually reaches its final economic settlement.
A buyer and seller may agree to a $100 million enterprise value, sign the purchase agreement and close the transaction. Yet the amount ultimately paid can still move after closing because the business is expected to be delivered with a normal level of working capital.
That is where the working capital purchase price adjustment comes in.
Working capital adjustments are now a standard feature of private-target M&A. SRS Acquiom’s 2026 Working Capital Purchase Price Adjustment Study, covering more than 1,500 private-target acquisitions valued at more than $385 billion, found that these adjustments are present in more than 90% of transactions in its dataset.
The principle is straightforward: a buyer generally expects to receive a business with enough ordinary operating working capital to continue functioning after closing.
If the seller delivers more than the agreed target, the seller may receive additional consideration. If the business is delivered with less, the purchase price can be reduced.
What Is Working Capital in an M&A Deal?
In basic accounting terms, working capital is:
Working Capital = Current Assets − Current Liabilities
But M&A working capital is not necessarily identical to the figure shown on a company’s balance sheet.
Deal agreements typically establish a specific contractual definition of net working capital (NWC). Cash is commonly excluded because cash is often treated separately in the enterprise-value-to-equity-value bridge. Certain debt-like liabilities, taxes, deferred revenue or other items may also be excluded or treated differently depending on the transaction.
SRS Acquiom notes that M&A net working capital commonly excludes cash and may contain deal-specific adjustments to determine which current assets and liabilities belong in the calculation.
That distinction matters because the adjustment is ultimately based on the definition negotiated in the purchase agreement not simply whatever number appears under “working capital” in the company’s financial statements.
The Working Capital Target or “Peg”
The central concept is the working capital target, sometimes called the peg.
The target represents the amount of working capital the buyer and seller agree the business normally needs to operate following closing.
Ideally, it reflects the company’s historical operating requirements after adjusting for factors such as:
- Seasonality
- Business growth
- Unusual transactions
- Changes in accounting practices
- One-time items
- Customer payment patterns
- Inventory requirements
- Changes in the company’s operating model
The target is normally negotiated during due diligence rather than determined for the first time after closing.
SRS Acquiom notes that the target is generally developed from historical balance-sheet information but may require adjustments for seasonality, extraordinary items, audit adjustments and other transaction-specific factors.
This is important because a poorly calibrated target can create a significant post-closing adjustment even when both parties acted in good faith.
The Basic Working Capital Formula
The basic purchase-price adjustment can be expressed as:
Working Capital Adjustment = Actual Closing NWC − Target NWC
Therefore:
Final Purchase Price = Preliminary Purchase Price + Working Capital Adjustment
For example, assume:
- Preliminary purchase price: $100 million
- Target NWC: $10 million
- Actual closing NWC: $12 million
The adjustment is:
$12 million − $10 million = +$2 million
The seller would therefore be entitled to an additional $2 million, making the adjusted purchase price:
$100 million + $2 million = $102 million
Now consider the opposite situation.
If actual closing NWC were only $8 million:
$8 million − $10 million = −$2 million
The final purchase price would become:
$100 million − $2 million = $98 million
The economics are simple: the buyer agreed to receive a business with $10 million of normalized working capital. Delivering $12 million creates a surplus; delivering $8 million creates a shortfall.
A More Complete M&A Purchase-Price Formula
Working capital is only one part of the broader purchase-price calculation.
A simplified enterprise-value bridge can be expressed as:
Equity Purchase Price = Enterprise Value + Cash − Debt ± Working Capital Adjustment − Other Agreed Adjustments
Suppose a transaction has:
- Enterprise value: $100 million
- Cash: $5 million
- Debt: $20 million
- Target NWC: $10 million
- Closing NWC: $8 million
The working capital adjustment is:
$8 million − $10 million = −$2 million
The simplified equity purchase price becomes:
$100M + $5M − $20M − $2M = $83M
This illustrates why an announced enterprise value should not automatically be interpreted as the seller’s final cash proceeds.
Actual transaction documents can contain additional adjustments, including transaction expenses, debt-like items, tax-related amounts and other negotiated provisions. The precise calculation is therefore determined by the purchase agreement.
Why Working Capital Can Become a Post-Closing Dispute
The mathematics are easy. The difficult part is deciding what belongs in the calculation.
Consider accounts receivable.
A seller may have $8 million of receivables on its balance sheet. But if some invoices are significantly overdue, the parties may disagree about the appropriate reserve or whether those receivables represent normal working capital.
Inventory can create a similar issue.
A manufacturer may technically hold $15 million of inventory, but some of it could be obsolete, slow-moving or unusually high relative to normal operations.
The same question applies to liabilities.
Should a particular accrued expense be included in working capital, treated as debt-like, or excluded altogether?
These are not merely accounting questions. They can directly change the amount one party ultimately pays or receives.
The American Bar Association has described working-capital adjustments as a mechanism through which the parties determine the working capital transferred at closing and compare it with the agreed target, with the difference producing an upward or downward purchase-price adjustment.
The Importance of Seasonality
Seasonality is one of the biggest reasons a simple historical average can produce a misleading working-capital target.
Imagine a retailer that generates most of its annual sales during the holiday season.
Its inventory and accounts payable may be substantially higher immediately before the holiday period than during other months.
If the transaction closes at that point, using an unadjusted annual average could make the business appear overcapitalized or undercapitalized when it is actually operating normally.
The target therefore needs to reflect the company’s normal working-capital requirements at the relevant point in its operating cycle.
This is one reason buyers and sellers often spend significant time analyzing monthly or even weekly historical working-capital levels during due diligence.
Estimated Working Capital vs. Final Working Capital
The process usually does not end on the closing date.
Because final financial information may not be available immediately, the transaction can close using an estimated closing balance sheet or estimated working-capital statement.
The parties then prepare a final calculation after closing.
SRS Acquiom notes that the buyer commonly has an opportunity to review and true up the estimated working-capital figure, with a typical review period of roughly 60 to 90 days in the process it describes.
The final number can therefore produce an additional payment from buyer to seller or seller to buyer depending on the difference between the contractual target and the final agreed calculation.
What Buyers Need to Watch
For buyers, the central question is:
Am I actually receiving the level of operating liquidity that the negotiated price assumes?
A buyer should pay particular attention to:
- Accounts receivable aging
- Inventory quality and reserves
- Accounts payable practices
- Accrued operating expenses
- Customer deposits
- Deferred revenue
- Seasonality
- One-time balance-sheet movements
- Changes in accounting policies
A seller that accelerates collections or delays ordinary payments immediately before closing could temporarily change working capital.
That does not automatically mean wrongdoing occurred. The important question is whether the resulting balance is consistent with the definition and normal operating practices established in the transaction documents.
What Sellers Need to Watch
For sellers, the priority is avoiding an artificially low purchase price caused by an overly aggressive working-capital target or an unfavorable interpretation of the closing accounts.
The seller should understand exactly how the target was calculated and how each major balance-sheet account will be treated.
A target that is too high can make a normal closing balance sheet appear deficient.
A target that is too low can have the opposite effect and create a benefit for the seller.
Because the adjustment is contractual, precision before signing can be more valuable than arguing about the number after closing.
Working Capital Is Really About Economic Continuity
The deeper purpose of a working-capital adjustment is not to punish either party.
It is to align the economic condition of the business delivered at closing with the condition that the buyer believed it was purchasing.
A company that normally requires $10 million of working capital should not be delivered with only $5 million if the purchase price was negotiated on the assumption that normal operating liquidity would transfer with the business.
Conversely, a seller should not necessarily receive a lower purchase price simply because the business temporarily experienced an unusual working-capital movement unrelated to its ordinary operations.
That is why the definition, target and methodology can matter as much as the final number.
The Bottom Line
In M&A, the headline purchase price is often only the beginning of the calculation.
Working capital adjustments provide a mechanism for reconciling the financial condition of the business at closing with the level of operating capital agreed upon during negotiations.
The core formula is simple:
Final Purchase Price = Preliminary Purchase Price + (Actual Closing NWC − Target NWC)
But applying that formula requires careful decisions about what counts as working capital, how the target is established, how seasonality is handled and how unusual balance-sheet items are treated.
For buyers and sellers alike, the lesson is straightforward: the purchase price is not truly final until the contractual purchase-price adjustments have been calculated and resolved.
In a well-structured transaction, the working-capital mechanism does not create a surprise after closing. It simply makes the final economics reflect what the parties actually agreed to buy and sell.
FAQs
What is a working capital adjustment in M&A?
It is a post-closing adjustment that compares the business’s actual closing working capital with an agreed target or peg. The difference can increase or decrease the purchase price.
What is the working capital peg?
The peg is the agreed level of normalized working capital that the buyer expects the seller to deliver at closing.
Can working capital increase the purchase price?
Yes. If closing working capital exceeds the agreed target, the purchase-price adjustment may increase the amount payable to the seller.
Can working capital reduce the purchase price?
Yes. If closing working capital falls below the agreed target, the purchase price may be reduced.
Is M&A working capital the same as accounting working capital?
Not necessarily. M&A agreements typically establish a specific contractual definition that can exclude or reclassify certain assets and liabilities.
How long does a working-capital true-up take?
The timing is determined by the transaction documents. SRS Acquiom describes 60 to 90 days as a typical period for the buyer’s review and true-up process in the transactions it discusses.
Disclaimer: This article is for informational purposes only and does not constitute legal, accounting, tax or investment advice. The treatment of working capital varies by transaction and is governed by the specific purchase agreement.
David Seidman is the Principal of Seidman Law Group LLC, where he serves as outside general counsel for small to mid-sized companies. A seasoned legal advisor and entrepreneur, he specializes in contract negotiation, commercial litigation, and strategic risk management across the hospitality and finance sectors.