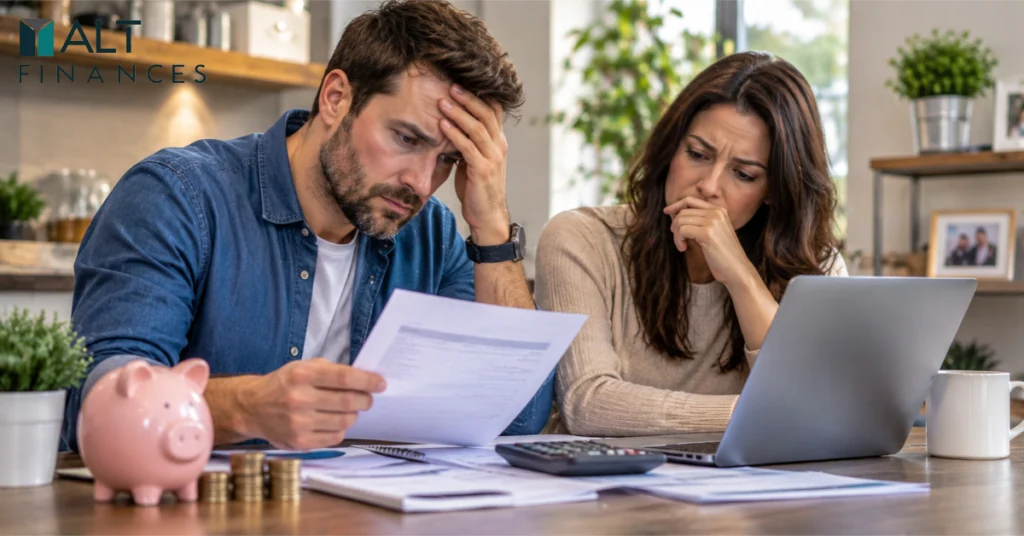
Financial pressure does more than affect a bank balance. Concerns about bills, debt, income and future security can influence how people evaluate choices, process information and respond to uncertainty. Understanding these effects can help people make more deliberate decisions, even when their financial circumstances are difficult.
1. When Money Worries Shape Everyday Life
Financial stress is often treated as a problem that can be solved simply by earning more or spending less. In reality, money worries can influence many areas of everyday life, including work, relationships, healthcare and personal decisions.
Someone worried about an upcoming rent payment, for example, may find it difficult to concentrate on a work project. Another person facing uncertain income might postpone a career change because the financial consequences feel too risky. Even ordinary decisions, such as replacing a household appliance or arranging a medical appointment, can become more complicated when money is tight.
The important issue is not just how much money someone has. It is also how secure they feel about meeting their obligations and handling unexpected expenses.
Financial stress and decision-making are closely connected because financial concerns can occupy attention that would otherwise be available for evaluating other choices.
2. The Psychology of Financial Stress
Financial stress develops when people feel that their financial responsibilities, available resources or future expectations are difficult to manage. It can result from debt, irregular income, rising living costs, unemployment or unexpected expenses.
One explanation comes from the psychology of scarcity. When people repeatedly worry about having enough money, their attention can become focused on immediate financial problems. This is sometimes described as tunnelling: urgent concerns take priority, while less immediate issues receive less attention.
For example, someone struggling to cover monthly bills may spend considerable time deciding which payment to make first. Planning retirement contributions or comparing long-term insurance options may become less urgent, even when those decisions matter.
Research suggests that financial hardship can be associated with changes in cognitive performance. A 2019 study involving 6,343 Australian adults found that periods of financial hardship coincided with declines in measured cognitive performance. However, this does not mean everyone experiencing financial pressure will have impaired judgment.
A separate 2024 study published in the Journal of Experimental Social Psychology found that experimentally induced financial stress reduced inhibitory control in a preliminary experiment. Its findings offer evidence of a possible connection between financial pressure and self-regulation, rather than proof that every financially stressed person makes poor decisions.
The distinction matters: financial stress is a response to circumstances, not a diagnosis of a mental health condition.
3. How Money Anxiety Changes Everyday Choices
Financial anxiety can influence decisions in several areas of life, although its effects vary according to personal circumstances, available support and the severity of financial pressure.
Shopping and household spending
A person concerned about money may become more cautious when buying essential items. They might compare prices more carefully, delay replacing an appliance or choose a cheaper product. These responses can be sensible, but constant uncertainty can also make even small purchases stressful.
Food and healthcare
Financial pressure can influence decisions about food quality, medical appointments and prescription expenses. Someone worried about household bills might postpone a dental visit or choose a cheaper food option. Such decisions may reduce immediate costs but create other problems if essential needs are repeatedly delayed.
Career decisions
A worker considering a better opportunity may hesitate if changing jobs means losing a stable salary, benefits or predictable working hours. Financial uncertainty can make the security of an existing position feel more valuable, even when another opportunity offers better long-term prospects.
Family and personal relationships
Money concerns can also affect conversations between partners and family members. Disagreements about debt, household expenses or financial responsibilities may create tension. Some people avoid discussing money because they fear conflict, while others may become overly focused on controlling spending.
These examples illustrate how financial pressure can influence the decision-making environment. They do not mean that everyone under financial stress responds in the same way.
4. Why Financial Pressure Encourages Short-Term Thinking
When an immediate expense needs attention, future planning can become harder to prioritise.
Consider someone with an irregular income who must choose between paying a utility bill and making a savings contribution. The immediate bill is likely to take priority because the consequences of missing it are clear and close. Saving for an expense several months away may feel less urgent.
This is not necessarily poor financial judgment. It can be a reasonable response to limited resources.
However, repeated pressure can create a pattern in which immediate problems consume most available attention. Decisions about debt repayment, insurance, education or retirement may be postponed because there is always another urgent expense.
A related response is avoidance. Someone worried about a credit-card balance might delay opening a statement or checking their account. Avoidance may temporarily reduce discomfort, but it can also make it harder to identify payment deadlines, interest charges or available repayment options.
Financial pressure can also produce excessive caution. A person may reject a potentially beneficial opportunity because the possibility of losing money feels unacceptable. In other situations, someone may accept expensive short-term credit because immediate relief outweighs the longer-term cost.
The underlying issue is that pressure can change how people weigh immediate needs against future consequences.
5. The Impact on Long-Term Financial Planning
Long-term financial planning requires people to consider future needs while managing current responsibilities. Financial anxiety can make that balance difficult.
Saving is one example. People who are uncertain about their ability to cover basic expenses may struggle to set aside money consistently. A savings target can feel unrealistic when unexpected bills repeatedly interrupt their plans.
Debt management can become equally difficult. Multiple balances, payment dates and interest rates require attention. When someone feels overwhelmed, they may focus on the creditor making the most urgent demands rather than comparing the overall cost of their debts.
Investing can also become emotionally challenging. Some individuals may avoid investing altogether because market losses feel especially threatening when their financial security is already uncertain. Others may take unnecessary risks in an attempt to recover from financial setbacks.
The latest research offers useful context. A study published in August 2026 examined economic insecurity and financial decision fatigue. It used European survey data involving 43,782 respondents and a separate three-wave survey of 1,512 digital finance users in China. The researchers found associations between economic insecurity, greater decision fatigue and lower reported well-being. The authors were careful not to claim definitive causation.
The Federal Reserve’s May 2026 report on the economic well-being of U.S. households in 2025, based on a survey of nearly 13,000 adults, also examines savings, income, expenses, employment, credit and financial hardship. It provides an important current picture of the financial pressures facing households, although its findings describe the United States rather than every economy.
6. Breaking the Cycle of Money Anxiety
Financial planning cannot remove every source of uncertainty, particularly when income, employment or living costs are outside an individual’s control. However, a few practical steps can make financial decisions more manageable.
Start with a clear picture of essential expenses. List regular income, housing costs, utilities, food, debt payments and other necessary expenses. A simple overview can help identify which obligations require immediate attention.
Break large decisions into smaller steps. Instead of trying to solve every financial problem at once, focus on one decision. This might mean reviewing one debt balance, checking an upcoming payment or comparing two service providers.
Build savings gradually. An emergency fund does not need to begin with a large target. Even a small amount set aside regularly can provide some protection against unexpected expenses. The appropriate target depends on income stability, household needs and existing obligations.
Address debt with accurate information. Write down balances, interest rates, minimum payments and due dates. This makes it easier to compare repayment options and avoid overlooking expensive borrowing.
Create a routine for financial reviews. Checking finances at a planned time can be more manageable than repeatedly worrying about them throughout the day. A short weekly review may be enough to identify upcoming obligations and necessary adjustments.
Seek help when the pressure becomes difficult to manage. A qualified financial counsellor or debt adviser may help with repayment options and budgeting. If money worries are seriously affecting sleep, relationships or everyday functioning, speaking with a qualified mental health professional may also be appropriate.
The Consumer Financial Protection Bureau’s research on financial preparedness highlights the relationship between emergency savings, financial shocks and people’s reported sense of financial control. Its findings support the value of building a financial cushion where circumstances allow, without suggesting that savings alone can solve every financial difficulty.
7. Conclusion: Building Better Decisions Through Financial Awareness
Financial stress affects more than spending choices. It can influence attention, confidence, career decisions, relationships and the ability to consider future needs. When financial concerns become persistent, even ordinary decisions may require additional emotional and mental effort.
The solution is not simply to tell people to become more disciplined. Financial pressure often reflects real circumstances, including unstable income, debt obligations and rising expenses. Better decision-making starts with understanding those pressures and identifying which choices can realistically be improved.
By organising essential financial information, breaking difficult decisions into manageable steps and seeking appropriate support, individuals can reduce some of the uncertainty surrounding money.
Ultimately, understanding the relationship between financial stress and decision-making helps explain why financial choices are not always purely mathematical. They are also shaped by the circumstances, emotions and pressures people experience every day.
Frequently Asked Questions
1. How does financial stress affect decision-making?
Financial stress can occupy attention, increase mental fatigue and make it harder to evaluate several options. Its effects vary depending on the person’s circumstances and the level of financial pressure.
2. Why does money anxiety make everyday decisions more difficult?
Persistent money worries can make people focus on urgent financial concerns. This may leave less attention for unrelated decisions involving work, family, healthcare or future planning.
3. Can financial stress lead to impulsive spending?
It can influence spending in different ways. Some people may seek immediate comfort through purchases, while others become extremely cautious. Neither response applies to everyone.
4. How does money anxiety affect long-term financial planning?
It may encourage people to postpone saving, avoid reviewing debts or become reluctant to invest. Immediate financial obligations can take priority over longer-term goals.
5. Can financial stress influence relationships and career choices?
Yes. Money concerns can contribute to disagreements about household expenses and make people more cautious about changing jobs, pursuing education or accepting uncertain opportunities.
6. What are practical ways to reduce financial anxiety?
Review essential expenses, organise debt information, build savings gradually where possible, break large decisions into smaller steps and seek professional support when needed.
7. How can better financial habits improve decision-making?
Regular financial reviews and organised records can make obligations easier to understand. They can also help people identify problems earlier and compare options more calmly.
Contributing Editor for Alt Finances, vision-driven with 20+ years in family office, asset management, and corporate development. Holds UN Special Consultative Status and is 100 Women in Finance Board Chair. Tulane University – A.B. Freeman School of Business.