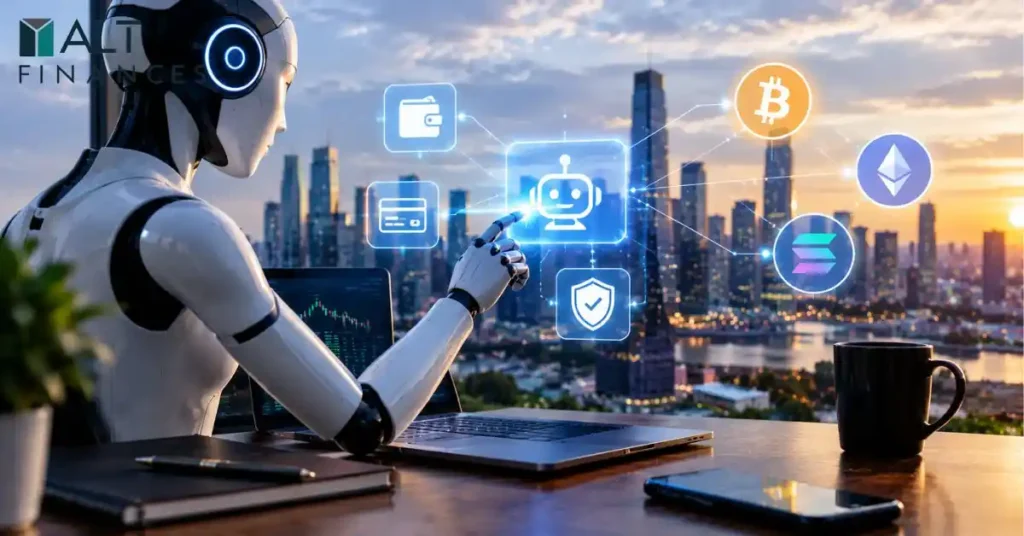
The next source of blockchain demand may come not only from people trading tokens, but also from software agents paying for digital services, purchasing data and interacting with other systems. If autonomous software becomes a meaningful participant in digital commerce, it could create a new category of users for cryptocurrency networks.
The investment question, however, is more complicated than whether AI agents will use crypto. Which networks could capture the resulting economic value, and would their native tokens benefit?
In 2026, the foundations for agent-driven transactions are becoming more tangible. Coinbase introduced Agentic Wallets in February, designed to let software agents spend, earn and trade within programmed security controls. Ethereum’s account-abstraction development is also making smart-contract wallets more flexible. These developments demonstrate that the technical building blocks are advancing, but they do not establish that autonomous agents have become a major source of sustained blockchain demand.
For investors, the distinction matters. More AI activity could increase demand for payment and settlement infrastructure. Whether that translates into durable token value depends on network economics, competition and how the resulting benefits are distributed.
Why AI Agents Could Become a New Source of Crypto Demand
AI agents differ from conventional chatbots because they can use tools, interact with software and carry out multistep tasks within defined permissions. Instead of simply recommending a service, an agent might locate a data provider, purchase access, retrieve information and use the results to complete a larger task.
Consider an agent that monitors a company’s supply chain. It could purchase updated shipping data, pay for a specialized forecasting service and request computing resources when demand spikes. If several providers operate independently, programmable payments could help automate these exchanges.
Traditional payment systems can support many such activities. Credit cards, bank transfers, prepaid accounts and centralized billing remain practical options, particularly when transactions involve established businesses and recurring subscriptions.
Blockchain becomes more interesting when transactions need to occur between parties that lack a shared account relationship, operate across borders or require programmable settlement. Stablecoins could allow agents to transfer digital dollars without each provider having to establish a conventional banking relationship with every customer.
Yet this is a potential use case, not proof of mass adoption. The economic advantage must exceed the costs of blockchain transactions, wallet management, compliance and security.
What Changed in 2026? From Agent Concepts to Payment Infrastructure
A significant development this year is the emergence of tools designed specifically for autonomous financial activity.
Coinbase introduced its Agentic Wallets on February 11, 2026. The product provides wallet capabilities for agents, including sending funds, trading and paying for services. Coinbase also describes integrations with its x402 payment standard, which is designed to support programmatic payments for APIs and other digital resources.
The significance is architectural: an agent can be given defined financial capabilities rather than relying on a person to approve every individual operation. Coinbase describes security controls such as spending limits and transaction monitoring. These features help address the risks of autonomous payments, although they cannot eliminate software vulnerabilities, compromised systems or poor permission design.
The company has reported more than 50 million transactions for x402. That is a company-reported measure of protocol activity, not independent proof of 50 million economically meaningful purchases by autonomous AI agents. Transactions can represent different use cases and values, so raw counts alone cannot establish commercial adoption.
Ethereum is developing another relevant part of the infrastructure. Its account-abstraction roadmap, updated in June 2026, explains how smart-contract wallets can support more flexible account management. Such capabilities can make transaction batching, recovery options and sponsored fees easier to implement.
These developments make agent-driven transactions more practical. They do not mean every agent needs a crypto wallet or that every payment must settle on-chain.
How Agent Activity Could Change Blockchain Economics
The potential effect on a blockchain depends on what agents actually do.
An agent that reads public blockchain data may generate no transaction fee because reading information does not necessarily change the network’s state. An agent that transfers tokens, executes a smart contract or settles a payment generally creates a transaction that must be processed.
That difference is fundamental. The number of agents interacting with a network is less important than the economic activity they generate.
Three channels could matter:
- Transaction demand: Agents making payments or executing contracts could increase usage of networks that provide cost-effective settlement.
- Infrastructure demand: Applications may require wallet services, reliable data, transaction routing, security monitoring and computing resources.
- Settlement reliability: Businesses may value networks that provide predictable costs, dependable execution and appropriate security for automated transactions.
Layer 1 blockchains and Layer 2 systems could compete for this activity. Main networks offer settlement and security properties, while Layer 2 systems can process transactions at lower costs by executing activity outside the base layer and relying on it for some combination of settlement and security.
However, cheaper transactions do not automatically mean stronger token economics. Lower fees may improve an application’s competitiveness while reducing revenue per transaction. High throughput can also increase activity without creating a proportionate increase in fees or demand for a network’s native token.
The relevant question is whether a network can serve agent-based applications competitively and capture enough economic value to sustain its infrastructure.
More Network Activity Does Not Automatically Mean More Token Value
This is the central investment issue.
A blockchain’s native token may serve several functions: paying transaction fees, securing the network through staking, providing collateral or participating in governance. The effect of additional agent activity depends on which of these functions creates incremental demand and how the protocol distributes economic benefits.
Suppose agents begin making millions of low-value payments. If each payment costs very little, the network may process substantial volume while generating modest aggregate fees. If those fees are paid in a token that users acquire only briefly, the impact on persistent token demand may be limited.
The outcome differs when increased usage creates meaningful demand for staking, collateral or other functions that require participants to hold the native asset. Even then, issuance, staking rewards, circulating supply and the distribution of fees affect the result.
There is also a distinction between the network and the application. An application may charge customers in stablecoins, retain revenue and pay relatively small network fees. Its operators could capture most of the commercial value while the underlying blockchain receives only a fraction.
Conversely, a network with meaningful fee demand and a credible mechanism linking usage to token utility may have a stronger economic connection between adoption and token demand.
Investors should therefore distinguish three measures:
- Usage: Is genuine economic activity taking place?
- Network economics: Does that activity generate sustainable fees or other benefits?
- Token value capture: Does the network’s design translate those benefits into durable demand for its native token?
None of these measures guarantees investment returns. Token prices also respond to liquidity, expectations, regulation, supply changes and broader market conditions.
Which Crypto Infrastructure Could Benefit?
The opportunity is unlikely to be limited to one AI-branded cryptocurrency. Several infrastructure categories could become relevant.
General-purpose blockchains provide smart-contract execution and settlement. Their competitiveness depends on security, developer adoption, fees and reliability.
Low-cost payment networks and Layer 2 systems may be attractive for frequent, small payments. Their challenge is to maintain sustainable economics while competing on price and transaction performance.
Wallet and authorization infrastructure can allow agents to operate with spending limits, defined permissions and transaction controls. This layer may create commercial opportunities even if the agent’s underlying payments use several networks.
Data and decentralized computing services could supply resources to agents. Their investment case depends on whether customers need decentralized provision and whether it competes effectively with centralized alternatives.
Agent-focused protocols may support service discovery, communication and payments between software systems. Many remain early-stage, and announcements or registrations should not be treated as evidence of recurring revenue.
This is where broader crypto infrastructure becomes relevant: the lasting opportunity may lie in systems that make digital transactions useful, secure and economical, rather than in tokens marketed around the AI narrative.
The Risks Behind the AI-Crypto Thesis
Autonomous financial activity introduces risks beyond ordinary blockchain volatility.
A compromised agent could be manipulated into sending funds to an attacker, purchasing fraudulent services or exceeding its intended budget. Malicious instructions, exposed credentials and excessive wallet permissions can turn a useful automation tool into a financial liability.
Smart-contract vulnerabilities and network outages create additional risks. Agents also need reliable ways to identify legitimate services, verify results and determine whether a transaction is appropriate. Blockchain settlement cannot guarantee that the underlying service delivered accurate information or fulfilled its promises.
Economic competition is equally important. Conventional payment providers may offer adequate speed, familiar compliance processes and established dispute mechanisms. If blockchain introduces more complexity without a clear advantage, businesses may choose traditional systems.
Finally, automated activity can inflate transaction statistics. Bots, incentives and speculative experiments may generate substantial activity without creating durable customer demand. Investors need evidence of repeat usage, genuine payments and sustainable economics rather than relying on transaction counts or token marketing.
What Investors Should Measure in Late 2026
A useful evaluation framework focuses on the relationship between real activity and economic value.
- Verified usage: Is activity generated by actual services and payments, rather than incentives or artificial transactions?
- Recurring demand: Do customers return after promotional programs or initial experimentation end?
- Competitive cost: Can the network provide settlement more efficiently than traditional payment systems or competing blockchains?
- Security and reliability: Are wallet permissions, transaction limits and recovery mechanisms appropriate for autonomous operations?
- Fee economics: Do network fees and other revenues justify the costs of operating and securing the system?
- Token value capture: Does increased usage create persistent demand for the native token, and how do issuance and supply dynamics affect that relationship?
Investors assessing digital assets should also distinguish a technically useful network from an attractively valued token. A strong product can succeed while its token delivers disappointing returns if the economic benefits accrue elsewhere.
The Next Phase of Crypto May Depend on Who Pays for the Network
AI agents could broaden blockchain usage by making software a more active participant in digital commerce. Payment standards, agent wallets and flexible smart-contract accounts are turning parts of that possibility into working infrastructure.
But the investment case remains conditional. Agents must have a practical reason to use blockchain, networks must deliver a competitive service, and the token’s economic design must connect adoption with meaningful demand.
The strongest projects may not be those with the largest AI claims or the highest raw transaction counts. They may be the ones that solve real payment, settlement or coordination problems at a competitive cost.
By late 2026, the technology is developing faster than the evidence of durable, agent-driven token economics. Investors should treat that gap as the central question not as proof that the opportunity is either inevitable or impossible.
Frequently Asked Questions
What are AI crypto agents?
They are AI-powered software systems that can interact with cryptocurrency wallets, blockchain applications or payment services to perform defined tasks, subject to their permissions and safeguards.
How could AI agents increase demand for blockchain networks?
They could generate payments, smart-contract interactions and settlement activity when blockchain offers practical advantages such as programmable transfers or permissionless access.
Will AI agents make crypto tokens more valuable?
Not necessarily. More network activity can increase usefulness without producing proportional token demand. Fees, token utility, supply dynamics and the distribution of economic benefits all matter.
How should investors evaluate AI-agent crypto projects?
Examine verified recurring usage, security, costs, network fees, competition and the specific mechanism linking activity to native-token demand. Avoid treating announcements or transaction counts as standalone investment signals.
Investment Disclaimer
This article is for informational and educational purposes only and does not constitute individualized financial or investment advice. Cryptocurrency investments are highly volatile and involve substantial risk, including the possible loss of principal.
Administrator at Alt Finances, leading editorial strategy and contributing in-depth coverage of investing, wealth management, alternative assets, and global financial markets. Through research-driven articles and analysis, he helps readers understand the ideas, industries, and market forces shaping modern finance.